
Sellers' Guide
How to Check How Many Years Are Left on Your Lease
A practical step-by-step guide to finding the remaining years on your lease, the common pitfalls (counting from the wrong date, missed extensions), what each length means for selling, and what to do if your lease is short.
Why Your Lease Length Affects the Sale of Your Flat
When you own a leasehold flat, you own the right to occupy the property for a fixed period of time, the lease term. This term counts down from the date the lease was granted. A new-build flat might start with a 125, 250 or 999-year lease, but over the decades, that term reduces. By the time you come to sell, the remaining term could be anywhere from over 200 years to fewer than 60.
Lease length matters because mortgage lenders impose strict minimum requirements. Most lenders want at least 70 years remaining when the mortgage starts, and many want 80 to 85. Mortgage terms now commonly run for 25 to 35 years, and lenders want the lease to run 30 to 40 years beyond the end of the term, so a lender granting a mortgage today typically wants the lease to run into the 2080s at least. A flat with 65 years on the lease may be genuinely impossible for most buyers to mortgage.
The result is that short-lease flats are effectively removed from a large proportion of the buyer market. The pool of potential purchasers shrinks to cash buyers or investors, which tends to push achieved prices down and lengthen the time the property sits unsold. Knowing where your lease stands determines which buyers can realistically make an offer, whether a lease extension would improve your position and whether there are other routes worth considering.
This guide is general information, not legal, financial or tax advice; check your own position with a solicitor or qualified adviser.
Three Ways to Find Your Lease Length
All three give you the same number. They differ in what else you get, what it costs and how long you wait.
The free LEASE tool
Cost: free. Time: about two minutes. Returns the lease dates and the exact term remaining, then estimates what extending would cost. Nothing to download.
How to use it →The Land Registry title register
Cost: £7. Time: a few minutes to download. The formal document a buyer's solicitor checks, showing the tenure, the lease term, the ownership and any charges.
How to get it →Your own lease and paperwork
Cost: free if you still have the lease. Time: as long as it takes to find it. The lease is the original source document, though you work out the remaining term yourself.
Where to look →Route 1: The Free LEASE Tool
The Leasehold Advisory Service (LEASE) is the government-funded body that gives leaseholders free advice. Its online calculator looks your flat up in HM Land Registry data and returns the date the lease started, the date it expires and the exact time remaining, down to the day.
You enter a full postcode, pick your flat from the leasehold titles found at that address, then verify an email address with a six-digit code. LEASE says that verification is needed because it has to confirm your identity and log an IP address in order to access Land Registry lease data, and it states the address will not be used for marketing.
Having found the term, the tool goes on to estimate what extending the lease would cost. LEASE asks for at least 50 years remaining, or 40 in central London. Below 40 years it gives you the length but no cost estimate, on the basis that pricing an extension that short needs a solicitor or valuer.
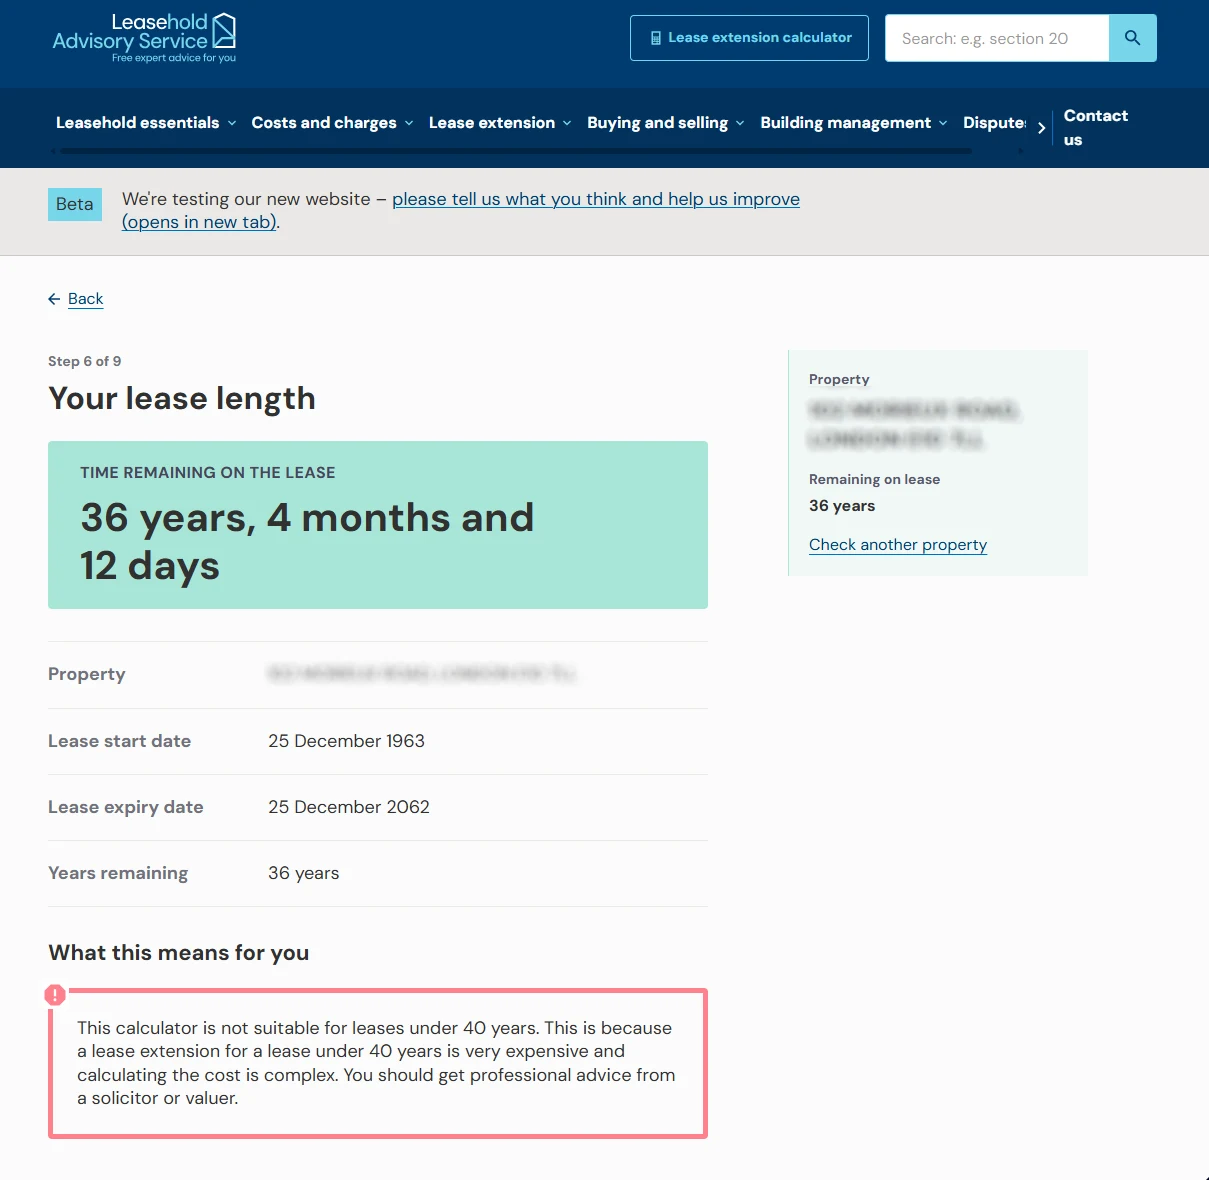
Two limits are worth knowing. A lease extended recently may still show its old term if the Land Registry record has not caught up. And the cost side is an estimate rather than a valuation, so treat it as a figure for planning rather than one to negotiate with.
Our news article on the free lease length and extension cost tool walks through all nine steps and covers what the tool leaves out.
Route 2: The Land Registry Title Register
HM Land Registry holds the official record of every registered property in England and Wales. The title register is where the lease term is formally recorded, and it is the document a buyer's solicitor will pull when your sale is under way. Getting hold of it early means you are working from the same source they will.
It settles a second question at the same time. Almost all flats in England and Wales are leasehold, but estate agent listings describe tenure loosely. A flat sold with a share of freehold still has a lease with a term that counts down: what you own alongside it is a stake in the company that holds the freehold, which makes extending easier but does not remove the need to check. The rare exceptions are commonhold flats and the occasional freehold flat. The register shows the property as leasehold with a term, or as freehold or commonhold, with no ambiguity. If yours turns out to be one of those, the rest of this guide does not apply, since there is no term to run out.
How to get it:
- Go to the property search. Visit the Land Registry property search on gov.uk.
- Find your flat. Enter your postcode and select the leasehold result for your specific flat.
- Buy the register. Pay £7 to download the title register.
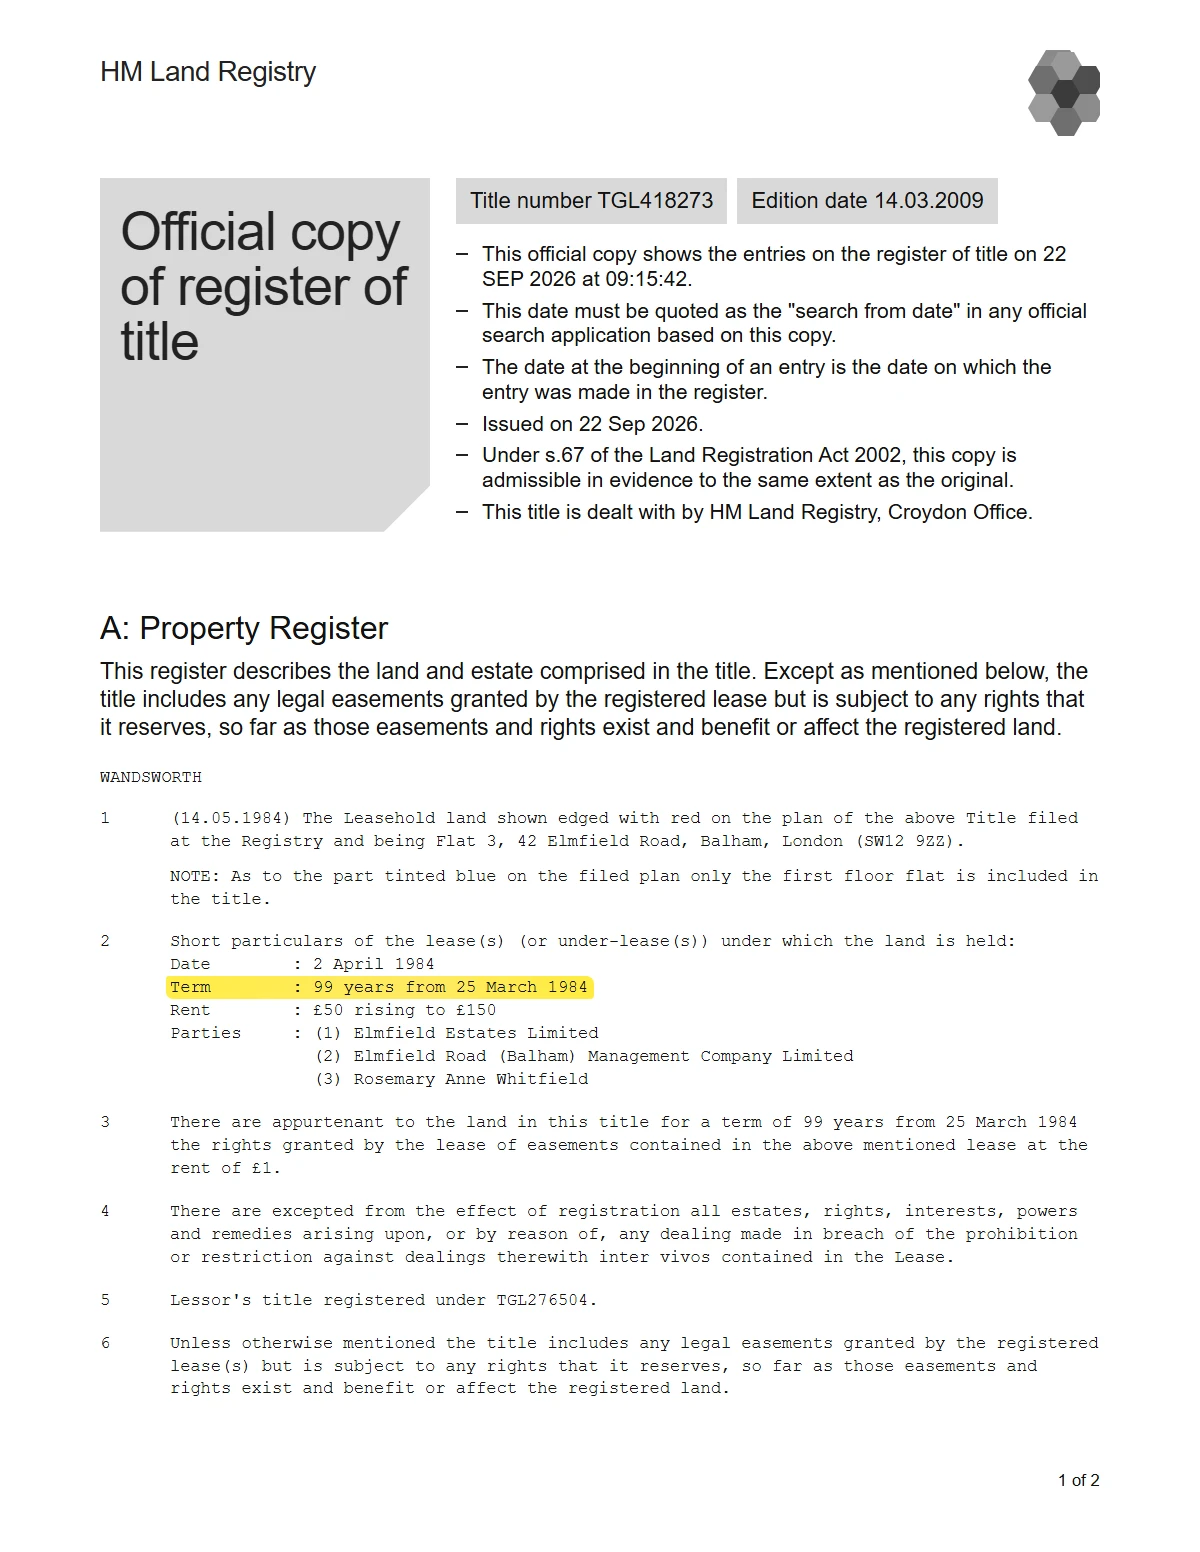
- Open the Property Register section. It shows the property description and the lease term.
- Read the term line. It is typically written as "Term: 99 years from 25 March 1984", as in the example below, or sometimes "Term: 125 years commencing 1 January 1990".
- Note both figures. You need the original term length and the start date to work out what is left.
Where the Registry holds a copy, you can also order the lease itself for £11 by post. The lease contains the full terms and any later variations.
If the lease has been extended at any point since the flat was first registered, the register should reflect it, either as a deed of variation or as a replacement lease.
Route 3: Your Own Lease and Paperwork
If you have a copy of the lease itself, usually handed over by your solicitor at purchase, you are holding the original source document. It states the date it was granted and the total term in years, either on the front page or in the early clauses.
Examples of how the wording looks:
- "A lease of [property] for a term of 125 years from 1 January 1990": original term 125 years, expires 1 January 2115. As at 2026, about 89 years remaining.
- "This lease grants a term of 99 years commencing 25 March 1985": original term 99 years, expires 25 March 2084. As at 2026, about 58 years remaining.
If the lease is not in your files, the solicitor who acted on your purchase should have a copy. Solicitors typically retain conveyancing files for 6 to 15 years, so older purchases may have been archived or destroyed. Lenders no longer routinely hold paper deeds, so if the solicitor's file has gone, the Land Registry copy is usually the quicker route.
Asking the managing agent or freeholder
Your managing agent or freeholder deals with the lease day to day and will usually know the term. It is a reasonable cross-check, though a weaker one than it used to be now that the lease length can be looked up free in a couple of minutes. What you get is normally a figure by phone or email rather than a document, so treat it as confirmation of a number you already have rather than the source of it.
Two practical points. If you pay ground rent, the demands you receive may reference the lease details, and service charge accounts and building insurance schedules sometimes do too. And managing agents change: whoever handles the building now may not hold the original records, while the freeholder is more likely to have them but slower to reply if they are not involved day to day.
How to Read the Number: Count From the Commencement Date
Whichever route you used, one thing catches people out more than any other. The lease term runs from the original commencement date, not from when you bought the flat. If the lease was granted in 1985 for 99 years, it expires in 2084 regardless of how many times the property has changed hands in between.
Worked example:
- Lease granted 1 January 1985 for 99 years.
- Mary buys the flat in 1985 (year 0). 99 years remaining.
- Mary sells to John in 1995. John buys with 89 years remaining (not 99).
- John sells to Sarah in 2015. Sarah buys with 69 years remaining.
- Sarah considers selling in 2026. The lease has 58 years remaining, regardless of when Sarah bought.
- 1985Mary buys, 99 years left
- 1995John buys, 89 years left
- 2015Sarah buys, 69 years left
- 2026Today, 58 years left
- 2084Lease expires
Each successive owner sees fewer years remaining; the lease does not reset on transfer. Counting from your own purchase date can overstate the remaining term by 10, 20 or 30 years and lead to costly surprises during a sale.
The reliable calculation: (commencement year + original term) - current year = years remaining. So 1985 + 99 = 2084; 2084 - 2026 = 58 years remaining.
Has the Lease Already Been Extended?
Lease extensions, whether statutory under the Leasehold Reform, Housing and Urban Development Act 1993 (the 1993 Act) or informally negotiated with the freeholder, modify the original term. A lease originally granted for 99 years from 1985 might have been extended in 2010 to add another 90 years, making the new effective term 189 years from 1985 (expiring in 2174).
Two ways an extension typically appears:
- Deed of variation agreed informally with the freeholder. In law this takes effect as a surrender of the old lease and the grant of a new one, but the paperwork is a single deed and Land Registry usually keeps the same title number. The register notes the deed and the new term.
- New lease, which is what a statutory extension under the 1993 Act always produces, and what some informal deals use too. The new lease replaces the original, and the register shows its date and its longer term.
If you bought the flat with an extended lease in place, your conveyancing pack should include the original lease and the extension document. If you arranged an extension yourself during ownership, you should have the deed of variation or new lease.
The title register is the safest single check, since any extension recorded against the title appears there. If it shows the original term only, and you have not extended the lease yourself, then the remaining term is calculated from the original commencement date as set out above.
Getting the Figure Right
Common ways the lease length gets misstated, all of which can cost you money, or a buyer's trust, once the sale is under way:
- "Long lease" in the listing. Marketing language with no precise meaning. Buyers and lenders need a number, and agents must give the remaining term as material information in any listing under the Digital Markets, Competition and Consumers Act 2024. Ask your agent for the exact figure and check it against the register.
- Third-party calculators that do not cite a source. Plenty of sites offer a lease length from a postcode without saying where the figure comes from. Useful for rough planning, not for the actual number. Anything that cannot tell you its source should be checked against the title register.
- Memory-based assumptions. "I think it was about 90 years when I bought it" is rarely precise enough for a sale. Mortgage lenders, surveyors and buyers' solicitors all want the exact figure.
- Estimates from the previous owner or estate agent. These can drift and are sometimes misremembered. Confirm independently.
For a sale, the figure that matters is the one a buyer's solicitor will independently verify against the Land Registry. Starting with the same source, and the correct calculation from the commencement date, removes any surprise mid-sale.
Understanding the Numbers
What Different Lease Lengths Mean for Selling
Not all short leases create the same problems. Here is a rough guide to what different remaining terms typically mean in practice.
125 years or more
No concerns relating to lease length. Buyers and mortgage lenders will not raise any issues. The flat can be sold in the normal way through an estate agent. The lease term is unlikely to be a factor in the sale at all.
90 to 124 years
Still comfortably within the range most lenders will accept. A small number of lenders may have specific requirements, but the lease length should not be a significant obstacle to sale. Standard marketing through an estate agent is suitable.
81 to 89 years
The lease is approaching the 80-year threshold, at or below which the cost of extending increases substantially. Most lenders will still lend at this level, but buyers and their solicitors may raise the lease as a concern. It is worth considering an extension before the lease reaches 80 years if possible.
70 to 80 years
At 80 years or less, marriage value applies to any lease extension, making it more expensive. Most lenders want at least 70 years, and many want 80 to 85, so the buyer pool starts to narrow here. Selling is still possible, but the number of buyers able to proceed without a lease extension in place is reduced.
60 to 69 years
Most mainstream mortgage lenders will not lend at this level. The realistic buyer pool is limited to cash buyers or investors, and those buying with the intention of extending the lease immediately after purchase. Achieving open market value through an estate agent becomes difficult.
Fewer than 60 years
Very few mortgage lenders will consider a flat at this level. The property is effectively a cash-only sale. The cost of extending the lease, if the leaseholder qualifies, will be substantial, and the market value of the flat will reflect the limited buyer pool. A specialist cash buyer is often the most practical route to sale.
The Critical Point
Why 80 Years Is Such an Important Threshold
The 80-year mark is the most important number in lease extension pricing. Understanding why matters if you are considering your options.
Under the Leasehold Reform, Housing and Urban Development Act 1993, qualifying leaseholders have a statutory right to extend their lease by 90 years at a peppercorn ground rent. The cost of doing so, the premium paid to the freeholder, is calculated using a formula that takes into account the current lease length, the property value, the ground rent, and the capitalisation and deferment rates used to value the freeholder's interest.
When the lease has more than 80 years remaining, the premium reflects only the freeholder's loss of ground rent income and the value of the reversion (what they get when the lease eventually expires). Once the lease has 80 years or less remaining, an additional element known as marriage value is added to the calculation.
Marriage value is the extra value the extension itself creates: a flat with a new long lease is worth more than the short-lease flat and the freeholder's interest added together. Once the lease is at 80 years or less, the leaseholder must pay the freeholder half of that gain on top of the rest of the premium. The chart below shows what this does to the cost of extending a flat worth £300,000 with a long lease. At 81 years the premium is about £6,000. Two years later, at 79, it is about £19,000, and by 60 years it has reached £40,000. The shorter the lease, the bigger the marriage value, so the gap keeps widening.
The Leasehold and Freehold Reform Act 2024 includes a provision to abolish marriage value, which would benefit leaseholders at 80 years or less. As of 2026 that provision is not yet in force; the secondary legislation has not been made. Treat any future abolition as a possible bonus, not a planning assumption: plan around the law as it currently stands.
The practical implication: if your lease is currently between 81 and 90 years, it is worth considering an extension sooner rather than later. Every year the lease counts down through this range, the future extension cost increases. Once it reaches 80 years, the cost increases more sharply.
Your Options
What to Do If Your Lease Is Short
If you have found that your lease is short, there are several routes available depending on your circumstances and priorities.
Option 1: Extend the lease before selling
If you qualify for a statutory lease extension, extending before you sell can substantially increase the pool of buyers and the achievable price. As of 31 January 2025, the previous two-year ownership requirement no longer applies, so the right is available from the day you become the registered owner. The process involves instructing a specialist solicitor and a surveyor accredited by RICS (the Royal Institution of Chartered Surveyors) to serve a formal notice on the freeholder and negotiate the premium.
This route takes time, typically six to twelve months, and involves upfront costs for the solicitor, surveyor and the premium itself. If your lease is still above 80 years, extending now rather than waiting will usually save money on the premium. If it is already at 80 years or less, the cost will be higher but an extension may still improve the sale outcome compared with selling with a short lease.
Before you instruct anyone, run the flat through the free LEASE calculator described in Route 1. It gives a rough premium in a couple of minutes, which is enough to decide whether an extension is worth pursuing before you pay for a formal valuation. Treat the figure as a planning number, not an offer.
Option 2: Sell at auction
Auction is a strong route for short-lease flats because the buyer pool is investor-led and expects them. The seller's solicitor usually prepares the legal pack, the auctioneer advertises the lot and competitive bidding on the day sets the price. Contracts exchange when the hammer falls and completion follows within 28 days, removing the chain risk and lender uncertainty that can derail a private treaty sale (the ordinary sale through an estate agent).
The price typically settles below open-market value, but for short-lease flats the gap is often smaller than at private treaty because the audience is already comfortable with the lease length. Best suited to flats where the lease is below 70 years or where a previous private treaty sale has stalled. See our auction guide for the full detail.
Option 3: Sell with the lease as it stands and negotiate
Some buyers, typically investors or developers, are willing to purchase a short-lease flat through a private treaty estate-agent sale and deal with the extension themselves after completion. In this case, the buyer will factor the cost of the extension into their offer, which means you will receive less than open market value. The upside is that you avoid the time and cost of the extension process yourself.
This approach is more straightforward when the lease still has 60 or more years remaining. Below this level, very few buyers can obtain mortgage finance, and the negotiation becomes more difficult because the buyer is taking on more risk and cost.
Option 4: Sell to a specialist cash buyer
A specialist cash buyer does not need mortgage finance and can therefore purchase a flat regardless of the lease length. This is often the most practical option when the lease is very short (below 70 years), when previous attempts to sell through an estate agent or at auction have failed, or when you need to sell quickly without the delay of a lease extension.
The offer will be below open market value, reflecting the complications involved. But for sellers who have been unable to sell through any other route, a cash buyer can provide a clear and certain path to completion. We have been buying short-lease flats since 2003 and know the legal and valuation issues that come with them.
For more on the cost calculation including marriage value, see our marriage value guide. For a fuller view of sale routes, see the options hub.
Related Reading
The valuation section covers marriage value calculations. The legal section covers ground rent issues that often interact with lease length. The guides hub covers the full range of seller reference guides.
Frequently Asked Questions
The quickest route is the free online tool from the Leasehold Advisory Service (LEASE), which reads HM Land Registry data and returns the lease start date, the expiry date and the exact time remaining once you have verified an email address. You can also check your original lease document, which states the start date and total term, and subtract the years elapsed. Buying the title register from HM Land Registry for £7 gives you the same term in the document a buyer's solicitor will check. Asking your managing agent or freeholder is a reasonable cross-check, though treat their answer as confirmation rather than the primary source.
No. The lease term runs from the original commencement date stated in the lease, regardless of how many times the property has changed hands. If the lease was granted in 1985 for 99 years, it expires in 2084 whether the current owner bought the flat in 1990, 2010 or last week. Counting from your purchase date is one of the most common errors and gives a misleading lease length.
Most mortgage lenders want at least 70 years remaining when the mortgage starts, and many want 80 to 85. Mortgage terms commonly run for 25 to 35 years, and lenders want the lease to run 30 to 40 years beyond the end of the term. Requirements vary, so it is worth checking the position of any lender involved in a sale.
Once a lease has 80 years or less remaining, the cost of extending it increases significantly because of a legal concept called marriage value. Marriage value is the increase in the property's value that results from the lease extension itself, and leaseholders must share half of this with the freeholder once the lease is at 80 years or less. This can add thousands of pounds to the cost of an extension and makes the flat harder to sell through an estate agent. The Leasehold and Freehold Reform Act 2024 includes a provision to abolish marriage value, but as of 2026 that provision is not yet in force.
An extension is usually recorded on the title register at HM Land Registry, either as a deed of variation or as a new replacement lease. When you check the title register (which costs £7 from gov.uk), look for any entries dated after the original lease grant: a deed of variation will reference the lease being amended, and a new lease will replace the original. If you have purchased the flat with an extended lease in place, your conveyancing pack should include a copy of the extension document.
Yes, but your options are more limited. Most mortgage buyers cannot purchase a flat with fewer than 70 to 80 years on the lease, which rules out a large proportion of buyers on the open market. You may be able to negotiate with a buyer who plans to extend the lease after purchase, but this is not straightforward. A specialist cash buyer is often the most practical route for sellers with a short lease who need a reliable and timely sale.
The cost varies considerably depending on the property value, current lease length, ground rent and the freeholder's approach. As a rough guide, for a flat worth £300,000 with a long lease, the premium would be around £6,000 at 81 years, about £19,000 at 79 years and about £28,000 at 70 years, plus solicitor and surveyor fees on both sides. The jump at 80 years is marriage value, which applies once the lease is at 80 years or less. A specialist leasehold solicitor or RICS surveyor can provide a more accurate estimate based on your specific circumstances.
In most cases, yes. Under the Leasehold Reform, Housing and Urban Development Act 1993, qualifying leaseholders have a statutory right to extend their lease by 90 years at a peppercorn ground rent. The two-year qualifying period was abolished by the Leasehold and Freehold Reform Act 2024, effective 31 January 2025, so the right is available from the day you become the registered owner. The process involves serving a formal notice on the freeholder and negotiating the premium, usually with the help of a specialist solicitor and a RICS-accredited surveyor. Some leases are excluded from the statutory process, so it is worth confirming your position with a solicitor before proceeding.