Flats accounted for 60 percent of the homes sold in London in 2025. That makes selling here a little different: the lease, freeholder and managing agent can matter just as much as the flat itself, and each can affect how smoothly a sale progresses. This guide explains the options available, the legal hurdles to expect, how long the process can take and the costs involved.
1 in 7 London sales makes a loss1 in 7 London sales makes a loss60% of London sales are flats9 in 10 London losses were flats
What Makes a London Flat Sale Different
Flats are not a niche part of the London market. They are the market. Around 54 percent of London households lived in a flat, maisonette or apartment at the time of the 2021 Census, while flats accounted for 60 percent of homes sold in London in 2025. For sellers, that means leasehold obligations, service charges and building management are part of everyday life. A sale may rely on a freeholder, managing agent or council to provide key information, so delays can arise even when your own paperwork is ready.
The average London flat costs £430,000, against £220,000 nationally.
60 percent of every home sold in London in 2025 was a flat.
22 percent of London purchases are cash, against 34 percent nationally.
What the lease says (the terms, restrictions and obligations it contains) can have more of an impact in London, compared to other parts of England. A short lease can make it harder for buyers to get a mortgage and may reduce the number of people able to proceed. High service charges, unusual ground rent provisions or unresolved disputes can also raise questions during conveyancing. Under the current rules, statutory lease extensions become significantly more expensive once a lease has 80 years or less remaining. With London property values generally higher than elsewhere in England, these issues can be large enough to affect the asking price, the buyer pool and how the sale is handled.
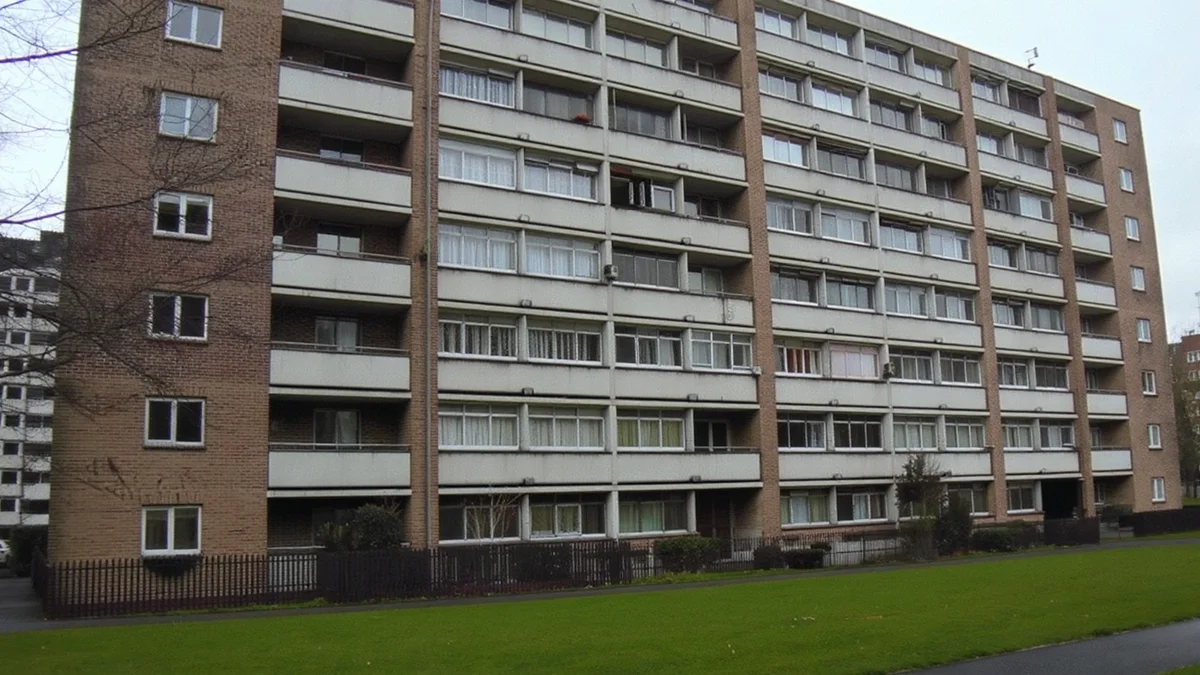
Who controls the building matters too, and London produces more variety here than most places. Right to Buy left the inner boroughs with a large stock of flats where the council is still the freeholder, while the Victorian and Edwardian terraces around them were divided into flats that the leaseholders often own between them. Add the post-2000 towers run by corporate managing agents and a single street can contain all three.
Each set-up creates its own delays. In a self-managed conversion, records may be patchy and responses depend on how organised the other owners are. Councils and large managed blocks usually have better records, but requests can sit in a queue and may involve extra paperwork on planned works and service charge liabilities.
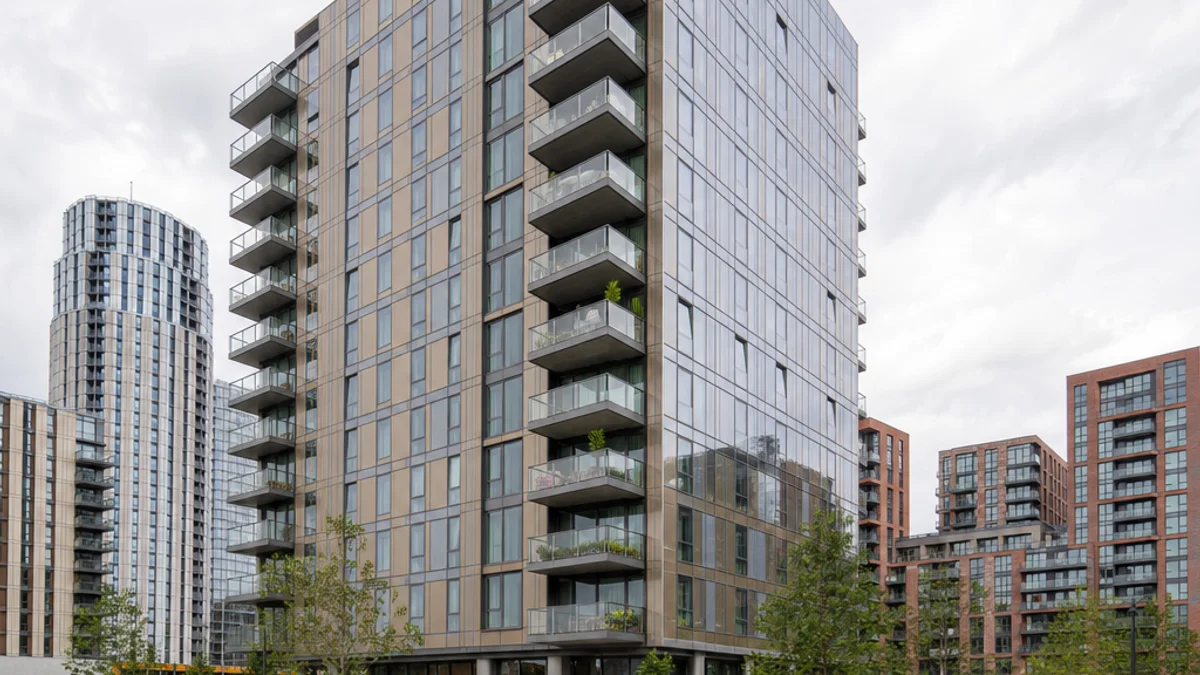
London's mix of buildings creates another distinction. One in nine London homes is in a block of six storeys or more, more than four times the English average, so external-wall and building-safety issues affect a larger part of the market here. Where there are concerns about cladding or other external-wall materials, a lender or valuer may require an EWS1 form or other evidence before lending. An EWS1 is not required for every block, but where one is needed it can become a significant part of the transaction. Older conversions bring a different set of risks, including outdated lease provisions, unclear repair responsibilities and historic disputes between owners.
The important point is that "a London flat" is not one type of property. A converted maisonette, an ex-council flat and a flat in a modern tower can be near neighbours, close enough to share a postcode, but the paperwork, management structure and risks to the sale can be completely different.
Those risks matter particularly under the private treaty system in England. An accepted offer is not legally binding until contracts are exchanged, so issues that surface during conveyancing can still trigger renegotiation, delay or a buyer pulling out weeks or months into the transaction. The more information you can assemble before a buyer's solicitor starts asking questions, the less opportunity there is for an avoidable problem to derail the sale.
London prices also change the buyer side of the equation. In June 2026, the average price paid by a first-time buyer in London was about £472,000, compared with about £245,000 across England. At that level, deposit size, mortgage affordability, family contributions, cash funds and the buyer's position in a chain can all have a material effect on how secure an offer really is.
Across England, leasehold is a minority tenure, accounting for 20 percent of homes, and most properties sold are freehold houses. London's far higher leasehold share feeds straight through into its sales market.
For a seller, that is the real difference. London does not operate under a separate set of property rules, but flats are more prevalent, leasehold is more common, high-rise housing is more concentrated and property values are higher. The result is a market where the details of the lease, the building and the buyer's finances can matter just as much as the condition of the flat itself.
Most of the sales, and nearly all of the losses
Share of all London sales in 2025
Flats 60%Houses 40%
Share of the London homes that sold at a loss in 2025
Flats 90%Houses 10%
Flats accounted for 60% of London sales last year, but represented 90% of homes that sold for less than their owner had paid. That is up from 78.4% in 2019. The figures come from Hamptons' research on seller gains in 2025, while the tenure data is from the government's 2024 to 2025 leasehold dwellings statistics.
Whether you are only starting to think about selling, already part-way through the process or dealing with a sale that has fallen through, the sections below cover the main decisions you will need to make. They explain your selling options, the legal preparation involved, realistic timescales and costs, what can affect your flat's value and the steps to take before putting it on the market.
Selling Options: What Are Your Choices?
Most sellers start with an estate agent and only consider auction or a direct sale if the conventional route runs into trouble. It is worth comparing the options before that happens. The right choice depends on what matters most to you, whether that is achieving the highest price, completing quickly or keeping the sale as straightforward as possible.
The flat itself may also narrow your options. A short lease, an unresolved EWS1 or another problem that makes mortgage lending difficult can rule out many conventional buyers, regardless of how you would prefer to sell.
There are three main routes to consider.
1. Estate agent (private treaty)
This is the most common route, and the one that typically achieves the highest price. The flat is listed on the major portals like Rightmove and Zoopla, marketed by the agent, and once an offer is agreed the sale proceeds with a single prospective buyer.
Pros: wide exposure to the open market, including mortgage-backed owner-occupiers who can finance most of the purchase price rather than paying entirely in cash. As a result, this route will usually achieve the highest sale price of the three options.
An owner-occupier can usually outbid an investor on the same flat. They are buying somewhere to live rather than an investment, so there is no resale margin to price in, and they avoid the 5 percent stamp duty surcharge that any additional-property buyer pays.
Cons: buyers are not legally committed until exchange, which can take months. Legal due diligence is mostly carried out after an offer is accepted, so issues like lease length, cladding or service charge arrears emerge mid-conveyancing. The leasehold management pack alone can take weeks to arrive from the managing agent. A sale that collapses at that stage leaves you back at the start, weeks of work later.
2. Auction
An auction sale is faster and far more certain than an estate agency sale. Marketing typically lasts 3 to 4 weeks, contracts exchange the moment the hammer falls and completion follows within 28 days.
Pros: the timetable is fixed, and the buyer is legally committed the moment the hammer falls. It suits flats with complications that mainstream mortgage buyers struggle with, such as short leases, cladding, non-standard construction and ex-local authority blocks. Competitive bidding can push the price well above expectations.
Cons: the guide price is set below market value to attract bidders, so on a quiet auction day the flat can sell at or near your reserve rather than for what it is worth. The timetable does not suit every seller either. Completion is 28 days after the hammer falls, so you need somewhere to move to by then and no onward purchase that could hold you up.
What auction achieves comes down to competition on the day. An unmodernised flat in a sought-after location can result in competitive bidding and a strong sale price.
Not all auctions work the same way, and choosing the right type matters. In a traditional unconditional auction the buyer is bound the moment the hammer falls and completes within 28 days. Under the Modern Method of Auction the buyer pays a reservation fee and gets a longer window to complete their research, with no exchange on the day, so you keep the competitive bidding but lose the certainty. Our guide to selling a flat at auction compares the two, and covers reserve pricing and the costs.
3. Direct sale to a cash buyer
Selling direct to a professional cash buyer bypasses most of the delays and risks of an estate agency sale. These companies typically promote their service as a quick, hassle-free way to sell.
Pros: it is the fastest route, typically 3 to 6 weeks and occasionally quicker where everything aligns, with no estate agent fees to pay. The flat is usually bought as-is, so there is no need for repairs or clearance. It also suits sellers who want certainty over the price: you agree a figure up front, so it does not hinge on a survey renegotiation or on how the bidding goes on auction day. It is particularly useful for flats in poor condition and for flats with a short or defective lease.
Cons: offers come in below open-market value, because the buyer is pricing in risk and a resale margin. Not every direct buyer is genuine either. Some are brokers acting as middlemen who never intended to buy the flat themselves, and some operators reduce their offer late in the process, a tactic known as gazundering. Leasehold is a specialism in itself, too. A firm that mainly buys houses may never have chased a managing agent for a management pack, worked through a defective lease or handled a cladding survey, and a buyer learning on your sale is a buyer who can stall or walk away. Before going any further with a direct buyer, first check that they buy leasehold flats. Then ask a couple of follow-up questions to test their experience: what makes a leasehold sale different from a freehold sale, and which stages are most likely to cause delays?
If you choose this route, transparency and trust matter most. Reputable companies conduct due diligence up front, explain how they reached the offer and stand by it. For a guide to the questions worth asking before agreeing terms with any quick-sale company, see our mistakes to avoid when selling to a quick-sale company guide.
London flats are what we buy. Our case studies include a short-lease flat in Wanstead, a studio in Hayes, a flat in poor condition in Hackney that exchanged in ten days, and an inherited flat in Paddington with under nine years left on the lease.
When the sale actually becomes binding
The difference between the three routes is not only the total time they take, but how much of that time you spend with a buyer who can still walk away.
Estate agent (private treaty)
Around four months waiting on an accepted offer that either side can abandon, then exchange with completion typically one or two weeks later.
Traditional unconditional auction
Three to four weeks of marketing, then contracts exchange the moment the hammer falls, and completion 28 days later.
Direct sale to a cash buyer
A short exposed stretch while the buyer runs its checks, then exchange and completion inside three to six weeks.
Week 0Week 8Week 16Week 24
Nothing binding yetContracts exchanged, sale committed
Each bar shows the typical timescale for that route, plotted on the same 24-week scale. The striped stretch is the part of the process a buyer can walk away from with no penalty, and it is where fall-throughs happen.
Legal Considerations
Leasehold flat sales usually involve more steps than freehold sales, partly because some of the information needed by the buyer's solicitor has to come from the managing agent or freeholder. That paperwork can take weeks to arrive, and it may lead to further enquiries about the lease, service charges, planned works or the way the building is managed.
Most leasehold sale problems fall into seven main areas: lease length, the management pack, service charges (including major works), ground rent, building safety, the lease itself (including defects, restrictions and consents), and information disclosure. Which ones affect you will depend on the building and how it is managed. London has everything from Victorian conversions to modern tower blocks, so the issues can vary considerably, and more than one may arise at the same time. Identifying them before you go to market can help prevent delays later.
There is also one related point worth covering: share of freehold. It is not a problem in itself, but if you jointly own the freehold it can change who provides the information and paperwork needed for the sale, so we cover it at the end of this section.
Lease length, and the 80-year cliff
London has many older leases. Flats granted on 99 or 125-year leases in the 1960s, 1970s and 1980s can now have much shorter terms remaining, and owners do not always know exactly how many years are left on their lease or what that could mean when they come to sell.
As a lease gets shorter, two separate issues become important.
The first is getting a mortgage. Lenders have their own rules about how many years must be left on the lease, both when the mortgage starts and when it ends. Most want 30 to 40 years still to run when the mortgage ends, and many look for 85 years or more at the start, though the figures vary by lender and change without notice. This means a shorter lease can reduce the number of buyers able to get a mortgage, even before it reaches the 80-year mark.
Prime central London can be different. Some lenders make exceptions for high-value short-lease properties, particularly where the freeholder is a major estate such as Cadogan or Grosvenor. These mortgages are usually considered under more specific lending criteria, so a short lease that would be difficult to finance elsewhere may still find a lender.
The second issue is the 80-year threshold. Under the current rules, once a lease has 80 years or less remaining, the cost of a statutory lease extension can rise significantly because marriage value becomes payable. Marriage value is the additional value created by extending the lease, and half of it is payable to the freeholder. This is why the difference between, say, 82 years and 79 years can be much more significant than the three-year gap suggests.
The Leasehold and Freehold Reform Act 2024 provides for marriage value to be abolished and a new valuation system to be introduced. Those changes are not yet in force, and the government is still working through the legislation and valuation rules needed to implement them. For now, sellers should plan around the current 80-year rule.
What crossing 80 years costs
What it costs to extend one flat's lease, shown at six different remaining terms. Value with a long lease £400,000, ground rent £100 a year.
95 years left
£5,500
85 years left
£8,000
82 years left
£9,000
80 years below this point the freeholder becomes entitled to half the marriage value
79 years left
£26,000
70 years left
£38,000
60 years left
£55,000
Look at what three years costs in each direction. From 85 years remaining on the lease to 82, the premium moves £1,000. From 82 to 79, three years later, it moves £17,000. Nothing about the flat has changed in between; only which side of the line the lease sits on. These are indicative figures for one flat rather than a valuation, and your own premium depends on the ground rent, the review clause and local values. Run your own through the LEASE calculator before deciding anything.
Waiting can therefore be expensive. A lease extension that is relatively affordable today may cost considerably more after the lease falls below 80 years, while the shorter lease may also make the flat harder to mortgage and sell.
As a general guide, there is usually less immediate pressure when a lease has more than 90 years remaining. Between 80 and 90 years, it is worth checking the likely cost of an extension and considering whether to extend before selling. At 80 years or less, the current marriage value rules can make an extension significantly more expensive. LEASE itself recommends considering an extension as the lease approaches 90 years.
You can also sell without extending the lease and leave the buyer to deal with it. Since 31 January 2025, buyers no longer have to own the property for two years before they can start a statutory lease extension claim, making this option more practical than it used to be.
The management pack contains the information a buyer's solicitor will usually need about the building and how it is managed. This can include service charge accounts and your current balance, ground rent, buildings insurance, planned major works, any lease breaches and building safety information. At the heart of the pack is the LPE1 form (Leasehold Property Enquiries), which is completed by the freeholder or managing agent.
You cannot put the pack together yourself. It has to come from the freeholder or managing agent, typically costs around £300 to £400 plus VAT, and can take 2 to 8 weeks to arrive. That wait can leave a leasehold sale sitting still even when everything else is ready to move.
Why a management pack takes 2 to 8 weeks
Nothing here is one long delay. It is four short ones stacked end to end, and only the first is inside anyone's control.
Days 1 to 3
Your solicitor requests the pack. This can only happen once you have instructed them, which is the argument for instructing early rather than waiting for an offer.
1 to 2 weeks
The managing agent requests payment. Most managing agents will not start work until the fee is paid, and a few still work through the post.
1 to 4 weeks
The agent compiles the answers. The slow parts are anything they have to go to someone else for: the insurance schedule, confirmation of consents for past alterations and the freeholder's answers on major works.
1 to 2 weeks
Accounts and the pack are issued. Certified service charge accounts often come from an external accountant, so this last leg depends on a third party too.
Significant service charge arrears can stop the pack being issued at all until they are cleared, which turns a four-week wait into an open-ended one.
Ranges are typical rather than guaranteed, and a well-run agent can beat all of them. The point is that three of the four stages sit with people you do not employ.
Timing matters. Some of the information in the pack can go out of date, so ordering it too early may mean paying for an update later. A good approach is to request it around the time you put the property on the market. Before then, you can clear any arrears and gather paperwork for alterations or works you have carried out, including any required consent. Our pre-listing checklist covers what to prepare in advance.
Service charges and Section 20 major works
Once the management pack arrives, buyers tend to focus on three things: the annual service charge, how much is held in the reserve fund and whether any major works are planned. A large increase in service charges or an expensive programme of works can lead to further questions or even a renegotiation of the price.
If major works are planned, there may be a Section 20 consultation. This is the process a freeholder must normally follow before charging any one leaseholder more than £250 for a set of works, or more than £100 a year under a long-term agreement. The process usually involves a notice of intention, a period for leaseholders to comment, details of the estimates and, in some cases, notice of why a particular contractor was chosen. If the correct consultation is not carried out, the amount recoverable can be limited unless the First-tier Tribunal grants dispensation. Our Section 20 guide explains the process in more detail.
Selling with a Section 20 notice
The awkward stage is the middle one, where everybody knows a bill is coming and nobody can put a figure on it yet.
1Nothing served
No major works in prospect. The accounts and the reserve fund balance are all a buyer has to weigh up, and the reserve fund usually helps you: money already set aside is money the buyer will not have to find.
2Notice of intention served
Works are coming, with no costings yet. This is the hardest point to sell at, since a cautious buyer prices in the worst case and a nervous one walks. If you can get the managing agent to put a ballpark in writing, it usually helps more than it hurts.
3Estimates issued
There is a number, so there is something to negotiate over rather than guess at. Expect the buyer to ask for it off the price, or for a retention held back at completion until the final figure is known.
4Contract awarded or works underway
The sum is settled and often already demanded. Awkward to fund, but straightforward to deal with: it goes into the completion figures like any other known liability.
Whatever the stage, it has to be disclosed. A Section 20 notice you have received is material information under the DMCC rules below, and a buyer who finds it in the pack having not seen it on the listing tends to lose confidence in everything else you have told them.
For a seller, what matters most is what the buyer discovers in the pack. Routine service charges are usually apportioned between buyer and seller on completion, but known or expected major works can be more complicated and may affect the negotiations. This can be particularly important in ex-local-authority blocks, where major works bills can run into tens of thousands of pounds for an individual flat.
Any disputes should also be disclosed. This can include past as well as current disputes with the freeholder, managing agent or other residents. An unresolved dispute is likely to prompt further enquiries, so it is generally better to deal with it early rather than let it emerge halfway through the sale.
Ground rent
Ground rent is an annual payment required under some leases. It is separate from the service charge and is not payment for a particular service. On many older London leases it may be a small fixed amount, such as £50 or £100 a year. On some more recent leases, however, the bigger issue is not today's ground rent but how the lease says it will increase.
Clauses that make ground rent rise sharply can cause problems with a mortgage. Ten-year doubling clauses are particularly difficult, and lenders may also look closely at ground rent linked to inflation or at rents that are high compared with the value of the flat. A common benchmark is 0.1 percent of the property's value, although lender rules vary. If the ground rent clause makes the property difficult to mortgage, one possible solution is a deed of variation agreed with the freeholder. Our ground rent guide explains the options in more detail.
One previous problem has now been removed. Until December 2025, a long lease with ground rent above £1,000 a year in London could fall within the assured tenancy rules, creating concerns for lenders if the ground rent went unpaid. Since 27 December 2025, leases of more than 21 years are excluded from those rules, so this is no longer an issue for new sales.
The government has also proposed capping ground rent on existing leases at £250 a year, reducing it to a peppercorn after 40 years. That proposal is included in the draft Commonhold and Leasehold Reform Bill but is not yet law, and a Commons committee has recommended cutting the 40-year period to 20. Sellers should not rely on it when planning a sale today.
Building safety, cladding and EWS1
Building safety can be a major issue when selling a flat in a larger block. A mortgage lender may ask for an EWS1 (External Wall System) form, which gives the lender information about the building's external walls and any cladding. It is not a legal requirement or a building safety certificate, and not every block needs one. Whether it is required will depend on the building, the external wall system and the lender.
If there are unresolved safety concerns or remediation is still outstanding, the sale can become more complicated. Some lenders will still lend where there is a funded remediation plan or the leaseholder is protected from the costs, but the lender may ask for additional evidence before approving the mortgage.
The Building Safety Act 2022 gives important financial protections to qualifying leaseholders in England. Broadly, the protections apply to long leases in buildings at least 11 metres high or at least five storeys where the lease was granted before 14 February 2022 and, on that date, the flat was the leaseholder's main home or the leaseholder owned no more than three UK homes. Qualifying leaseholders do not have to pay for historical cladding remediation, and their liability for certain other historical building safety costs is limited.
Importantly, the status belongs to the lease rather than the person buying it. If the lease qualified on 14 February 2022, those protections pass to future buyers. If it did not qualify on that date, selling the flat to someone who would otherwise meet the test does not make it qualifying.
The paperwork matters during a sale. A buyer's solicitor may ask for the leaseholder deed of certificate and the landlord's certificate, which help establish what protections apply and who may be responsible for remediation costs. If you have already completed a leaseholder deed of certificate, keep a copy ready for your solicitor.
If your landlord has formally asked you to provide a leaseholder deed of certificate and you have not done so, deal with it before going to market. Until a valid certificate is provided, the lease may be treated as non-qualifying, even if it would otherwise meet the test.
The financial difference can be significant. A qualifying leaseholder is protected from historical cladding remediation costs and has protection against certain other costs. A non-qualifying lease may have less protection, although that does not automatically mean the leaseholder must pay the full remediation bill, as other legal protections or funding arrangements may apply.
Our EWS1 and cladding guide explains the EWS1 process, leaseholder protections, certificates and what they can mean when you sell.
Two lines that decide what applies to your building
Building safety rules use two important height thresholds: 11 metres and 18 metres. London has a particularly high concentration of taller residential blocks, so these rules affect a large number of flats in the capital.
Building height is measured from ground level to the floor of the top storey, not to the roof. This means a building with a roof above 11 metres may still fall below the 11 metre threshold when measured in the way the legislation requires.
1
2
3
4
18m
11m
1Victorian conversion. Three storeys with high ceilings (typically 3.2m). The floor of the top storey is only around 6.4m above ground level. Even if the roof ridge rises above 11m, the roof does not count for this measurement. The building therefore falls below both the 11m and 18m thresholds.
2Modern low-rise block. Five storeys at 2.7m each. The floor of the top storey is at 10.8m. Under 11 metres, but it meets the five-storey threshold and is therefore a relevant building under the Building Safety Act: the category that brings the leaseholder protections into play.
3Mansion block. Six storeys, top floor at 14.5m. Sits in the 11 to 18 metre band.
4Tower block. Eight storeys, top floor at 19.6m. Over 18 metres and in the most scrutinised band.
The white dashed line on each block is the floor of its top storey. That is the level the 11 and 18 metre tests measure to, so it is the dashed line you compare against the yellow ones, not the roof above it. Floor-to-floor heights vary, which is why the two tests can disagree, so count the storeys of your own block as well as estimating its height.
A building is in scope for the leaseholder protections if it contains at least two dwellings and is either at least 11 metres high or at least five storeys. Meeting one of those is enough. Basements do not count as storeys and rooftop plant rooms are excluded from both tests. The lease itself then has to qualify as well, on the 14 February 2022 test set out above. Where a leaseholder can be charged for non-cladding safety defects, the lifetime cap is £15,000 in Greater London against £10,000 elsewhere. That cap rises to £50,000 where the lease was worth over £1m and £100,000 over £2m, which in London is not a rare case. Flats worth under £325,000 in Greater London pay nothing at all.
Lease defects, restrictions and consents
Sometimes the problem is the lease itself. Many London flats are in older converted houses, and some of their leases were drafted decades ago. When the buyer's solicitor checks the lease, they may find a defect such as a missing right of access or support, no clear responsibility for repairing or insuring part of the building, or service charge percentages that do not add up properly. In other words, there may be nothing wrong with the flat itself, but the legal paperwork can still cause a problem.
Where lease problems hide
One converted London terrace, and the five places a buyer's solicitor finds problems the seller never knew were there.
Top flat
Middle flat
Ground flat
P
12345
1The roof. Someone has to be clearly obliged to repair and insure it. In old conversion leases, sometimes nobody is.
2A knocked-through wall. Structural changes usually needed the freeholder's consent as a licence to alter, and the paperwork outlives the work.
3The hallway and stairs. Your lease has to grant a legal right to reach your own front door over the common parts.
4The flat below. Each lease should grant rights of support and shelter between the flats. A missing one is invisible until a solicitor looks for it.
5The parking space. Sometimes it is in the lease; sometimes it is an arrangement that has always worked and has no legal basis at all.
Every one of these is invisible on a viewing and visible in the lease, which is why they surface during conveyancing rather than before the offer. The sixth hiding place is arithmetic rather than architecture: the service charge shares across the building should add up to 100 percent, and separately drafted conversion leases do not always manage it.
Lease defects often become an issue when the buyer needs a mortgage. The buyer's solicitor will usually also act for the lender and must be satisfied that the title is acceptable before mortgage funds can be released. If the lease contains a serious defect, it may need to be dealt with before the sale can proceed.
There are two common solutions. A deed of variation changes the wording of the lease, but usually requires the freeholder's agreement. An indemnity policy does not correct the defect, but provides insurance against the risk. Indemnity insurance may not be available if the issue has already been raised with the freeholder, so speak to your solicitor before contacting the freeholder or managing agent about it.
Two ways to deal with a lease defect
One option corrects the lease itself; the other insures against the risk. Contacting the freeholder about the defect too soon can rule out the insurance option.
Speak to your solicitor before raising a defect with the freeholder or managing agent. Once the freeholder has been approached, the indemnity route usually closes.
Deed of variationCures the defect
What it does
Rewrites the faulty wording in the lease itself, permanently, for you and every future owner.
What it needs
The freeholder's agreement and signature, then registration at HM Land Registry.
Typical cost
£1,500 to £4,000 in legal fees, plus any premium the freeholder asks for.
Typical time
8 to 16 weeks with a willing freeholder; months with a slow one.
Indemnity policyInsures the risk
What it does
Pays out if the defect ever causes a loss. The lease itself stays exactly as it is.
What it needs
An insurer willing to quote, and a freeholder who has never been approached about the issue.
Typical cost
A one-off premium, usually £200 to £1,500 on a flat sale.
Typical time
Days. A policy can be put in place mid-sale without involving anyone else.
Neither is automatically the better route. Indemnity insurance only works where the risk is genuinely dormant, and the buyer's mortgage lender has the final say on whether a policy is acceptable for a given defect; some insist on the lease being varied. Costs and timings are the typical ranges from our detailed guides, and your own quotes can sit outside them.
Alterations are one of the most common consent problems. Many leases require the freeholder's permission for structural or layout changes, usually through a licence to alter. Problems can arise where an owner has removed a wall, moved a kitchen or converted a loft without getting that consent.
The management pack and TA7 property information form both ask about alterations, so any missing consent is likely to come to light during the sale. Depending on the circumstances, the solution may be retrospective consent from the freeholder or indemnity insurance. If the work changed the layout, it is also worth checking that the lease plan still matches the flat, as any difference is likely to prompt further enquiries.
Lease restrictions can also reduce the number of potential buyers. A ban on subletting may rule out buy-to-let investors, while restrictions on pets or alterations may put off some owner-occupiers. Parking is another point to check carefully. In some blocks, a parking space is provided under a separate licence or informal arrangement rather than forming part of the lease, so make sure the listing accurately reflects what is legally included. Our guide to selling with a no-subletting clause explains that issue in more detail.
Disputes can cause further complications, whether they involve the freeholder, managing agent or another leaseholder. These might range from noise complaints to formal allegations of a breach of the lease, and they may need to be disclosed during the sale.
A missing freeholder can create a different problem altogether. If the freeholder cannot be found, there may be nobody available to grant consent, sign a deed of variation or answer enquiries. It does not necessarily prevent a sale, but it can change the process. Our guide to selling with a missing freeholder explains the options.
The simplest precaution is to read through the lease before you put the flat on the market. Check for restrictions, consent requirements, parking rights and anything that no longer matches the property as it stands today. Our guide to reading your lease shows what to look for.
Material information disclosure (DMCC Act 2024)
Since 6 April 2025, estate agents have been required under the Digital Markets, Competition and Consumers Act 2024 to give buyers the material information they need to make an informed decision. For a leasehold flat, this is likely to include key details such as the tenure, remaining lease length, ground rent, service charge and any known issues that could affect a buyer's decision, such as major works or building safety concerns.
The legal responsibility sits mainly with the estate agent, but most of the information will come from you. If the service charge is wrong, a Section 20 notice is missed or another important issue is overlooked, the listing may later conflict with the management pack. That can lead to further questions, delays or an attempt by the buyer to renegotiate the price.
The awkward part is timing. A leasehold sale is often a process of discovery, and sellers may not know everything when the property first goes on the market. Some information only becomes clear once the management pack is ordered, the freeholder or managing agent answers enquiries, or the buyer's solicitor starts examining the lease. At the same time, ordering the management pack months in advance is not always practical because some of the information can go out of date and may need to be refreshed later.
The sensible approach is to provide everything you reasonably know at the outset. Most of the basic information should already be available from documents you hold, including the lease, your latest service charge and ground rent demands, recent accounts, any Section 20 notices and relevant building safety paperwork. The formal management pack can then follow at the appropriate point, and the listing can be updated if something important emerges.
Being open about issues from the start can also make the sale more secure. A buyer who knows about the service charge or planned works before making an offer can take them into account from the outset. Finding the same information several weeks later during conveyancing is much more likely to prompt questions or a renegotiation. Our guide to disclosure mistakes covers the main pitfalls in more detail.
Share of freehold
Share of freehold is often found in London conversions, where the flat owners jointly own the freehold, usually through a company in which each owner has a share. Importantly, you still own your flat on a lease, so the lease length, obligations and responsibilities still matter. What changes is who deals with the freehold side of the sale.
If the building is self-managed, there may be no managing agent to prepare the usual paperwork. Instead, the insurance documents, accounts, service charge information and meeting minutes may need to be gathered by one or more of the other owners. This can be quicker than dealing with a managing agent, but only if everyone is organised and responds promptly.
If the freehold is owned through a company, there are two simple checks worth making before you sell. First, make sure the company is active and its Companies House filings are up to date. Second, check that you have the share certificate or other evidence of your interest in the company. If records are missing or the company has fallen behind with its filings, sorting them out can delay the sale. The share will also need to be transferred to the buyer when the flat is sold. Our guide to buying the freehold collectively explains how these arrangements come about.
Why leasehold sales are more likely to fall through
The private treaty system in England and Wales is fragile enough for any sale, but leasehold adds more work, more third parties and more issues that may only come to light after an offer has been accepted.
Buyers may offer before their finances are confirmed. An offer can be accepted before the buyer has provided proof of funds or secured a mortgage agreement in principle. With leasehold, the risk is greater because the lender may later raise concerns about the lease length, ground rent, service charges, building safety or another issue affecting mortgageability.
More problems can emerge during conveyancing. Leasehold sales involve extra documents and enquiries, often involving the freeholder or managing agent. Short leases, missing consents, major works, building safety issues or defects in the lease may not become clear until the legal work is already underway.
Those extra enquiries create more time for the sale to unravel. Delays waiting for management information or answers from third parties can stretch the process out, giving buyers more time to reconsider, lose their mortgage offer or become nervous about something they discover.
The buyer can still walk away before exchange. An accepted offer is not legally binding in England and Wales. So even after weeks of leasehold enquiries and paperwork, the buyer can withdraw before contracts are exchanged.
Timescales: How Long Will It Take?
The time it takes to sell a leasehold flat in London depends mainly on which sale route you choose. The table below gives a realistic guide for each method of sale.
Method
Typical timescale
Private treaty
3 to 6 months (often longer)
Auction (traditional unconditional)
7 to 8 weeks from instruction to completion
Direct sale
3 to 6 weeks (occasionally faster where everything aligns)
Private treaty
This is usually the slowest of the three routes. Viewings may start within days of the flat going on the market, but most delays happen after an offer is accepted. The buyer still needs to arrange their mortgage, their solicitor has to review the lease, and the management pack must come from the managing agent or freeholder. Any one of these can take weeks. If the buyer pulls out before exchange, the sale may have to start again with someone new.
Auction
A traditional unconditional auction follows a fixed timetable. The flat is usually marketed for 3 to 4 weeks before the auction. If it sells, contracts are exchanged as soon as the hammer falls, and completion normally takes place within 28 days. With the key dates set from the start, there is much less uncertainty than with a typical estate agency sale.
Direct sale
This is usually the fastest route. A cash buyer does not need a mortgage, so there is no lender approval or mortgage valuation to wait for. Most direct sales complete in around 3 to 6 weeks, and sometimes sooner if the title is straightforward and the paperwork is ready.
In some cases, completion can take as little as 7 days. This is more realistic where an earlier estate agency sale has fallen through late in the process, as the management pack may already be available and many of the legal enquiries may already have been answered. A cash buyer can then pick up much of that work rather than starting from scratch.
What causes delays?
Slow responses from freeholders or managing agents
Missing leasehold paperwork
Mortgage delays on the buyer's side
Survey or valuation issues, especially where cladding is involved
Tip: if you are working to a fixed date (an onward purchase, an estate completion, an emigration deadline), auction or a direct sale will give you certainty that an estate agency sale cannot.
The costs of selling a flat are broadly similar across the country, but London's higher property prices make percentage-based fees more expensive. For a typical London flat, total selling costs are often around £5,000 to £10,000, depending on the sale price and how complex the leasehold arrangements are.
Estate agent fees: 1% to 2% plus VAT. On a £400,000 flat, that is £4,000 to £8,000 before VAT, or £4,800 to £9,600 with it.
Solicitor or conveyancer: £800 to £1,500 plus VAT. Higher where the leasehold structure is complex. Our guide to choosing a conveyancing solicitor covers what to ask before instructing.
Leasehold management pack (LPE1): £300 to £400 plus VAT. Some managing agents charge more for premium developments. See what the LPE1 form contains.
EPC (Energy Performance Certificate): £50 to £100. Required by law before marketing.
What comes off a £400,000 sale
This example uses mid-range figures for an estate agency sale, so you can see roughly how much of the sale price you keep and where the rest goes.
£400,000 agreed sale price
Estate agent commission, £7,200. 1.5 percent plus VAT
Conveyancing, £1,440. £1,200 plus VAT for a leasehold sale
Management pack, £420. £350 plus VAT from the managing agent
EPC, £75. Needed before the flat can be marketed
About £390,900 before any mortgage is redeemed
In this example, the cost of selling is around £9,100. Any outstanding mortgage and early repayment charge are dealt with separately and are not included in that figure.
You also need to allow for the ongoing cost of owning the flat until the sale completes. Service charges, ground rent, council tax and buildings insurance will continue to run, so a sale that takes several months can become noticeably more expensive, particularly in larger managed blocks with high service charges.
With a direct sale, there is no estate agent commission to pay.
How to reduce costs
Compare fixed-fee conveyancing quotes, including online and high street firms.
Ask whether the managing agent can send leasehold documents electronically to avoid extra postage or administration charges.
If you are considering auction, check whether the auction company offers legal pack preparation on a no sale, no fee basis.
If you already paid for an LPE1 or management pack for an earlier buyer, ask your solicitor whether it can still be used before ordering another one.
Market Conditions and London-Specific Factors
The market for flats can vary considerably across London, not just from one borough to another but from one street or development to the next. As of June 2026, the average price of a London flat or maisonette was 4.7 percent lower than a year earlier, compared with a 2.5 percent fall across the London market as a whole. Flats are therefore facing a more price-sensitive market than many other types of property.
For sellers, the closest competition matters most. A flat in a popular area with good transport links may attract strong interest, but buyers will still compare it with similar properties nearby. In larger developments, several near-identical flats may be for sale at the same time, making price, condition, floor level, outside space and service charges particularly important.
Leasehold issues can also affect demand in a way that does not apply to most houses. Buyers and their lenders will look at the remaining lease length, ground rent, service charges, planned major works and the building safety position. A flat with a straightforward lease and manageable running costs will usually appeal to a wider pool of buyers than one with a short lease, high service charges or unresolved building issues.
This means two similar flats can perform very differently in the same market. One may attract offers quickly, while another in the next block takes much longer because of its lease, service charges or building management. When pricing a London leasehold flat, general London or borough-wide trends are only a starting point. The figures that matter most are recent sales and competing flats in the same building and immediate area.
Where the falls are: Inner London flats
Change in average price over the 12 months to June 2026. The London fall is mostly an Inner London flats story; Outer London is close to level.
Flats and maisonettes
All property types
Inner London
Flats-7.7%
All property-6.4%
Outer London
Flats-1.4%
All property+0.1%
England
Flats-2.3%
All property+1.8%
No change
Annual change in the average price paid, 12 months to June 2026, from the UK House Price Index published by HM Land Registry. Inner London is the ring of central boroughs, from Westminster and Camden round to Tower Hamlets and Southwark; Outer London is everything beyond it. Figures are revised as late sales are registered.
Flat prices by borough: the two ends of the table
Change in the average price of a flat over the 12 months to June 2026. The five biggest falls are all in prime central London; the five biggest rises are all in the outer boroughs.
Five biggest falls
Westminster-25.7%
City of London-20.4%
Kensington and Chelsea-15.3%
Hammersmith and Fulham-13.7%
Tower Hamlets-13.2%
Five biggest rises
Kingston upon Thames+1.6%
Southwark+1.7%
Havering+1.8%
Redbridge+2.0%
Barking and Dagenham+2.2%
No change
Annual change in the average price paid for a flat or maisonette, 12 months to June 2026, from the UK House Price Index published by HM Land Registry. Borough figures rest on a few hundred sales a month at most, and in Westminster and the City of London on far fewer, so the largest swings are revised more than most. Treat the order as a guide, not a league table. Eight of the 33 boroughs saw flat prices rise over the year; London as a whole was down 4.7 percent.
What Kind of London Flat Do You Have?
Location sets the price of a London flat. The building decides whether it sells, and how smoothly. Lease length, the service charge, building-safety paperwork and the way the block is managed all feed into how confident a buyer feels, and whether a lender will offer a mortgage at all.
That is why two flats on the same street, on the market at the same price, can have very different sales. One goes through without a hitch. The other stalls once the buyer's solicitor starts reading the lease.
Most London flats fall into one of five broad types, and each brings its own lease, management and repair issues. Working out which one you have shows you where buyers and their solicitors will look first.
Victorian or Edwardian conversion
Inner suburbs, from Walthamstow to Clapham. A terraced or semi-detached house split into two to four flats, usually in the 1970s or 1980s.
What decides the sale The paperwork, and who has to produce it. These blocks are often share of freehold, so there may be no managing agent to ask. The buyer's solicitor goes to one of the other owners in the building instead, for the documents and the answers to enquiries, and the sale then moves at whatever pace that neighbour manages.
There is often no sinking fund either, meaning no pot of money set aside for big repairs. If the roof needs replacing, or something structural goes wrong, the cost arrives as a single bill split between two or three owners, rather than being spread across the dozens of flats in a larger block.
Almost always under both height thresholds, so cladding and EWS1 questions usually do not arise.
Purpose-built mansion block
Central and inner London: Marylebone, Maida Vale, Kensington, St John's Wood. Red brick or stone, built between the 1890s and the 1930s.
What decides the sale The service charge, and whether the block is heading into a round of major works. Lifts, porters, communal heating and a listed facade all cost money to keep going, so a buyer weighs up the yearly running costs alongside the asking price.
Lease length is worth checking too. Many of these blocks were split into flats and sold on long leases decades ago, so the term left can be shorter than owners expect.
Usually in the 11 to 18 metre band, so a lender may still ask questions about the external walls.
Ex-local-authority block
Across the inner boroughs, Southwark, Lambeth, Hackney and Tower Hamlets in particular. Bought under Right to Buy, then resold on the open market.
What decides the sale Whether your buyer can get a mortgage. Some lenders are wary of deck-access flats, where the front doors open onto an outdoor walkway. Others are wary of taller blocks, or of estates where the council still rents out most of the homes. Your pool of buyers can shrink before anyone has even viewed the flat.
Major works are the other issue. When the council repairs the roof, the lifts or the outside walls, it bills you for your share, and those bills can run into tens of thousands of pounds. A buyer who hears that work is coming will usually lower their offer or walk away.
If it was bought under Right to Buy in the last ten years, check the discount repayment window and the council's right of first refusal before you market it. We buy ex-local-authority flats directly, which takes the lender question off the table.
Suburban purpose-built block
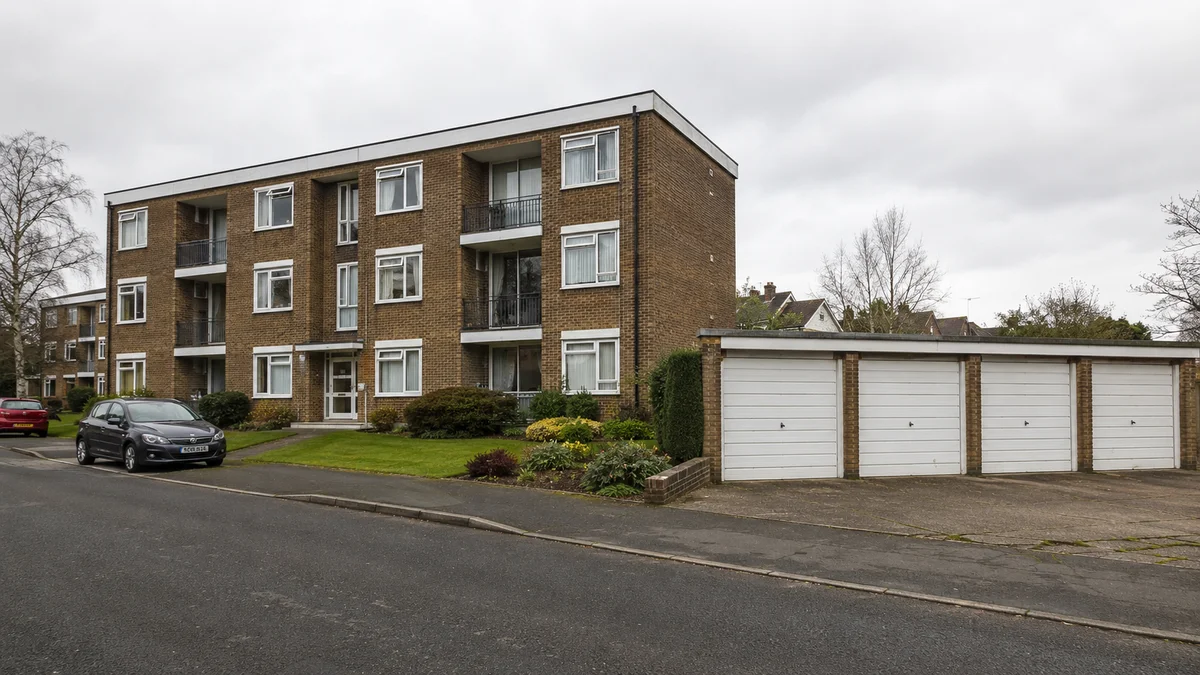
Outer London, Zones 4 to 6. Two, three or four-storey blocks built between the 1930s and the 1970s, often set back behind grass and garages.
What decides the sale Lease length, more often than anything else. A 99-year lease granted in 1972 has about 45 years left today. Most lenders will not lend on a lease that short, so your buyer will probably have to pay cash. Extending the lease costs more by that stage too, as the premium you pay the freeholder climbs once the term drops below 80 years.
The sums are hardest on lower-value flats. You pay for a valuation and for two sets of legal work, your own and the freeholder's. Those fees barely move with the value of the flat, so they take a far bigger bite out of the total on a cheap flat than on an expensive one.
Normally below both height thresholds, and normally managed by an agent rather than the leaseholders.
Post-2010 tower or regeneration block
The Docklands, Nine Elms, Stratford, Wembley, Croydon and the larger regeneration sites. Often bought off-plan.
What decides the sale Three things at once, usually. Lenders want to know where the building stands on its external walls, meaning whether the cladding and insulation have been checked and signed off. Buyers look at the service charge, which runs high in a block with lifts, a concierge and a gym. Both will read the ground rent review clause, the part of the lease that sets how much your ground rent rises and how often.
Competition inside your own building matters just as much. A tower with hundreds of near-identical flats can have several of them on the market at the same time. Buyers have more choice, and that caps how far above the last recorded sale in the block you can push your price.
The new-build premium paid on the original purchase is not usually recoverable on resale, which is a large part of why this group shows up in the loss-making figures.
Why being closer to the centre did not protect prices
Owners tend to assume that the closer a flat sits to the middle of London, the better it holds its value. In 2025 it did not work that way. Tower Hamlets, Kensington and Chelsea and Westminster recorded some of the highest shares of loss-making sales in the country, in some cases approaching 20 to 30 percent of all sales. Cheaper outer boroughs came off better.
The Hamptons research behind those figures points to four causes, and none of them is really about geography:
Owners who bought at the 2021 to 2022 peak paid top prices, and many are now selling for less than they paid.
Higher borrowing costs cut what buyers can afford, and they bite hardest where prices are highest.
Flexible working let first-time buyers look further out, where the same money buys more space.
Developers finished large numbers of new flats in exactly the areas now showing the worst figures.
Central and near-central boroughs are simply where all four overlap.
For a seller, this comes down to comparables: what similar flats near you have actually sold for. A borough or zone figure tells you very little about your own flat. Look at what sold in your block, and in the two or three most similar blocks nearby, at what price and how long each one took. That is the number to price against, and it costs nothing to check.
Valuation: What Affects the Value of a London Flat?
Size and location set the starting point. Five other things move the figure up or down:
Lease length: a short lease cuts what your flat is worth, and below 80 years many lenders will not lend on it at all.
Service charges: buyers add the service charge to the mortgage payment when they work out what they can afford, so a high charge, or major works on the way, puts them off.
Building safety: a flat sells at a discount while questions about the cladding remain open, because the buyer cannot easily get a mortgage on it.
Market trends: prices have not moved the way most owners expect. Expensive central boroughs, Kensington and Chelsea, Westminster and Tower Hamlets among them, have recorded some of the highest shares of loss-making sales, while cheaper outer boroughs have held up better.
Transport and schools: buyers pay more for a short walk to a station, an Elizabeth line stop in particular, and for a place in a good school catchment.
What to do before you put the flat on the market
If your lease is close to 80 years, at 81 or 82 say, start looking into extending it now. Under the current rules, once it drops below 80 you also pay marriage value, a share of the extra value the extension creates. A statutory extension takes 6 to 12 months, so starting early keeps that cost off the bill and widens the pool of buyers.
Look up recent sold prices in your postcode, and in your own block where you can find them.
Ask local agents what the flat is worth with the lease as it stands, and what it would fetch with a longer one. The gap tells you whether to extend before you sell.
Next Steps: How to Prepare for Sale
Five things to sort out before the flat goes on the market:
Instruct a solicitor before you accept an offer. One who is already appointed can start the day you agree a sale, rather than a fortnight later while you are still ringing round for quotes.
Gather your documents. You will need the lease, the service charge accounts, your ground rent records and the LPE1, the standard information form your managing agent or freeholder fills in. A building with cladding may also need an EWS1 form, which records the safety of the external walls. If the block is at least 11 metres or five storeys tall, ask the freeholder for the landlord's certificate and fill in your own leaseholder deed of certificate, as the buyer's solicitor will ask for both. Our pre-listing checklist sets out the full list.
Get two or three valuations. Ask local estate agents, and a specialist cash buyer for the lower benchmark, then check both against sold prices for similar flats on Rightmove or Zoopla.
Choose how you want to sell. An estate agency sale, an auction and a direct sale to a cash buyer trade price, speed and certainty against each other in different ways. Pick the one that fits what matters most to you.
Get the flat ready. Clear the clutter, clean it properly and have the EPC to hand, along with any certificates or guarantees for work you have had done. Presentation moves the price more than most sellers expect.
Tackle the Issues Early
The leasehold issues that most often derail sales (slow managing agents, lease length, ground rent, cladding) are predictable. Tackling them early, before a buyer is even on the table, is the single biggest thing a seller can do to improve the odds of a clean sale.
This page is general information rather than legal, financial or tax advice. Specific situations should be discussed with a solicitor.
The tenure shares come from the leasehold dwellings statistics for 2024 to 2025, published by the Ministry of Housing, Communities and Local Government (MHCLG), the government department responsible for housing in England: 20% of homes in England are leasehold, rising to 39% in London, the highest share of any region.
The accommodation-type shares come from the ONS bulletin Housing, England and Wales: Census 2021: 54.0% of London households lived in a flat, maisonette or apartment, against a range of 11.4% in the East Midlands to 21.6% in the South East across the other English regions.
The first-time buyer prices come from HM Land Registry's UK House Price Index for England, June 2026, published 19 August 2026: £471,629 in London against £245,450 across England. The same release puts the average flat or maisonette at £431,036 in London against £219,154 across England. UK HPI figures are revised in later releases.
The cash-buyer shares come from Hamptons' research in The power of cash buyers: 22% of London purchases were made without a mortgage, against 34% across Great Britain and 49% in Wales, making London the lowest region. The figures cover 2023 to date. Prime central London runs the other way, at around half of purchases.
The legal position on this page rests on the following:
Building Safety Act 2022, for the leaseholder protections and the certificates a buyer's solicitor will ask to see.
Leasehold and Freehold Reform Act 2024, for the abolition of the two-year ownership rule and the marriage value provisions still waiting to be brought into force.
The fee ranges, timescales and valuation figures are our own, drawn from buying leasehold flats in London since 2003. They describe what is typical, not what is guaranteed, and an individual flat can sit well outside them.
Further Reading
Three related pages cover the practical detail behind the choices on this page: the stage-by-stage timeline of a typical leasehold sale, the common pitfalls when dealing with quick-sale companies, and real examples of London flats we have bought.
If speed is the priority, the two routes that move fastest are sale by traditional unconditional auction (typically 7 to 8 weeks from instruction to completion) and direct sale to a cash buyer (typically 3 to 6 weeks, occasionally faster where everything aligns). Both bypass the chain risk and mortgage delays of a private treaty sale through an estate agent.
A private treaty sale through an estate agent typically takes 3 to 6 months and can run longer if leasehold complications emerge. A traditional unconditional auction takes 7 to 8 weeks. A direct sale to a cash buyer typically completes in 3 to 6 weeks, occasionally faster where everything aligns.
The EWS1 (External Wall System) form is an industry-developed external-wall assessment, used mainly by mortgage lenders and valuers when a building has cladding or external-wall fire-safety questions. It is completed by a competent professional, typically a chartered fire engineer, chartered surveyor or chartered building engineer. It is not itself a statutory selling document, but without one many lenders will not lend on a flat in a relevant building, which can collapse a sale or limit the buyer pool to cash buyers. See the RICS guidance on the EWS1 process for the current position.
Typical total costs are £5,000 to £10,000 in fees and disbursements: estate agent commission (1 to 2 percent plus VAT), solicitor or conveyancer fees (£800 to £1,500 plus VAT), the leasehold management pack (£300 to £400 plus VAT), an EPC (£50 to £100) and an auction legal pack if applicable (£300 to £600).
You can, though it changes who is able to buy. Once the lease drops below 80 years, the value falls and many mortgage lenders will not lend, leaving cash buyers and investors. Options include extending the lease before sale or selling unextended to a cash or auction buyer who plans to extend after completion. The old workaround of serving a Section 42 notice and assigning it to the buyer was needed because of the two-year ownership rule, which was abolished on 31 January 2025 by the Leasehold and Freehold Reform Act 2024; a buyer can now serve their own notice after completion.
The main causes are slow freeholder or managing agent responses, late discovery of lease length or service charge issues, missing fire safety documentation and the fact that under the private treaty system in England and Wales buyers are not legally committed until exchange of contracts.
A traditional unconditional auction works well when your flat has complications a mortgage buyer would struggle with, such as a short lease, cladding issues, structural concerns or non-standard construction. It also gives you certainty: contracts exchange immediately when the hammer falls, with completion typically 28 days later. See our auction guide for more.
The lease itself, the leasehold management pack (LPE1) from the managing agent or freeholder, recent service charge accounts, ground rent statements, an EPC and where applicable an EWS1 fire safety form. Gathering these early avoids weeks of delay during conveyancing.
Tenanted flats are commonly sold to landlords and investors, and the rental income can be a selling point. Since 1 May 2026 the Renters' Rights Act 2025 has replaced assured shorthold tenancies with periodic tenancies and abolished Section 21. Getting the flat back empty now means the tenant leaving by agreement, or serving a Ground 1A notice. That needs four months' notice, cannot be used in the first 12 months of the tenancy, and stops you re-letting or marketing the flat for rent for 12 months after the notice expires. Our guide to selling a tenanted flat covers both routes.
Get multiple valuations: from local estate agents, from a specialist cash buyer and where possible from a surveyor registered with the Royal Institution of Chartered Surveyors (RICS). Cross-check against recent sold prices for similar flats in the same building or postcode using portals like Rightmove or Zoopla.
Get a Cash Offer for Your London Flat
Specialist cash buyer of leasehold flats. Offers in days, completion in weeks.