A house converted into two flats but registered as a single freehold title creates complications for buyers, mortgage lenders and solicitors. Two routes are available: split the title into separate leases first, or sell the whole property as one. This guide covers both.
Clean splitting costs £3,000 to £7,000Mortgage buyers need separate leasesClean splitting costs £3,000 to £7,000Cash investors buy unsplit titles
Why One Title Creates Complications
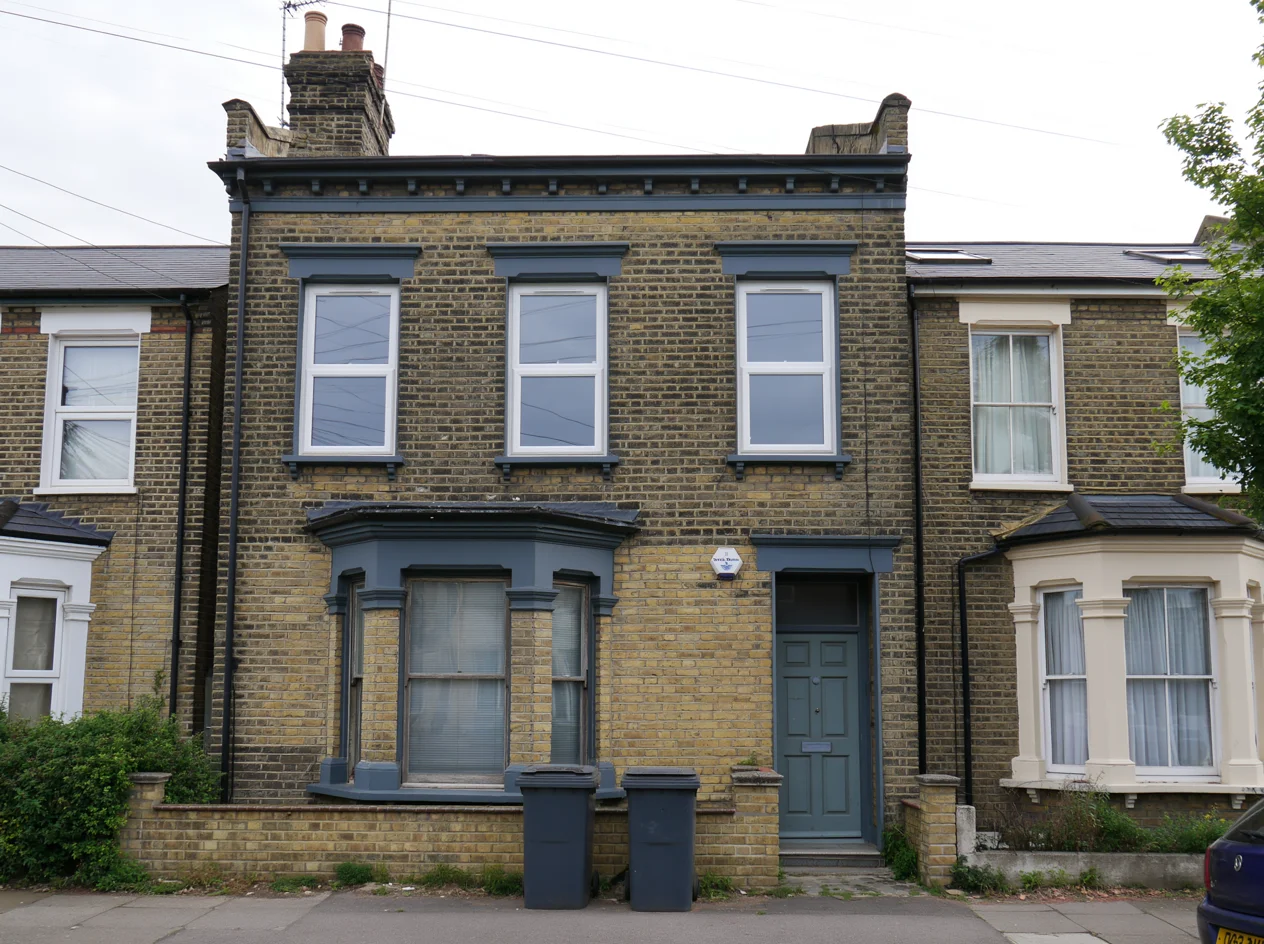
A Victorian or Edwardian terraced house that has been divided into a ground-floor flat and a first-floor flat is a common type of property in many cities across England and Wales. In many cases these conversions happened decades ago, and the owner at the time simply continued to hold the freehold title to the whole house, without ever creating separate leasehold titles for each flat.
This creates a problem when it comes to selling. Mainstream mortgage lenders will not lend on a flat that does not have its own registered leasehold title. A buyer for the ground-floor flat using a mortgage cannot proceed if the flat is not a separately registered leasehold, even if the conversion is perfectly sound structurally and the flats have always been let or occupied separately.
The result is that you typically cannot sell each flat individually to a mortgage-backed buyer unless you first create separate leases. Without doing that, two routes remain: sell the whole property as a single freehold title to a single buyer, or sell to a cash investor or developer who can accept the unusual title structure and either hold the property as one or split it themselves after purchase.
One Title Today, Three Titles After the Split
Splitting does not change the building; it changes the paperwork that describes it.
Before: one title
One freehold titleYou own the whole house: both flats, the structure and the land beneath.
Ground-floor and first-floor flatsNo separate titles. Neither flat can be mortgaged or sold on its own until a lease is created for it.
After: three titles
Freehold titleRetain it, transfer it to a management company or sell it. It sits over both leases.
Leasehold title: ground-floor flatIts own registered title: mortgageable and saleable on its own.
Leasehold title: first-floor flatIts own registered title: mortgageable and saleable on its own.
The split turns one unmortgageable whole into two mortgageable flats, with the freehold sitting above both. The building itself does not change.
This guide covers both routes, the legal mechanics of splitting the title, the planning and building regulations position, the costs and timing, as well as who the realistic buyers are.
Your Two Main Options
Each route has different costs, timescales, buyer pools and net proceeds. Both are valid; the right choice depends on your circumstances.
Option 1: Create Separate Leases, Then Sell
A solicitor drafts two long leases (typically 99 to 999 years), one for each flat, which are registered at HM Land Registry. Each flat then has its own leasehold title and can be sold individually to mortgage-backed buyers at full market value. This route takes longer and costs more upfront, but typically yields higher total proceeds than selling the property as one.
Best for: sellers who want the highest total price and are prepared to invest several months and £3,000 to £7,000+ in legal and compliance work upfront (more where regularisation is needed).
Option 2: Sell the Whole as One Freehold
Sell the entire property, both flats under one freehold title, to a single buyer. The buyer will typically be a cash investor, property developer or experienced landlord who intends to either create leases themselves after purchase or use the building as a buy-to-let. Simpler, faster and lower upfront cost, but usually achieves lower total proceeds than selling the flats separately.
Best for: sellers who want speed and certainty, do not want to manage the splitting process or where the conversion has planning issues that would slow the splitting route significantly.
What Splitting the Title Involves
Creating separate leasehold titles from a single freehold is a legal process carried out by a solicitor with experience in title splitting. Done properly, it produces two cleanly registered leasehold titles, each individually saleable and mortgageable.
What Each Title Covers After the Split
The two leases carve out the flats; the freehold keeps the structure, the shared hallway and the land.
Each lease covers one flat; the freehold keeps everything the flats share. This is the structure buyers' solicitors and lenders expect to see.
The four-step process
1. Instruct a solicitor. A solicitor experienced in title splitting drafts the two leases. Typical lease terms are 99, 125 or 999 years. The leases need to clearly define the extent of each flat, the shared parts (entrance hall, stairs, roof) and the obligations of each leaseholder.
2. Hire a surveyor. A surveyor registered with the Royal Institution of Chartered Surveyors (RICS) produces accurate floor plans and measurements for each flat, which become part of the lease. This is essential for the Land Registry to register the two leases without boundary disputes later.
3. Register the leases at HM Land Registry. The solicitor lodges the two leases for registration. Each new leasehold title gets its own title number and can then be dealt with independently.
4. Decide what happens to the freehold. The freehold title still exists and now sits over both leasehold flats. You can retain it (becoming the landlord), transfer it to a management company jointly owned by the leaseholders or sell it separately. See "What happens to the freehold" below.
What goes into each lease
Each lease defines the extent of the flat (the demised premises), the rights granted (to use shared parts, drainage, services), the obligations of both leaseholder and freeholder (repairs, insurance, service charges) and any restrictions (pets, alterations, subletting). Standard lease provisions also cover ground rent (a peppercorn, meaning zero: the Leasehold Reform (Ground Rent) Act 2022 bans financial ground rent on new long residential leases), the term and how the lease can be enforced or extended in future.
Get this right at the splitting stage. A poorly drafted lease can cause problems for buyers' solicitors and lenders later, sometimes requiring deeds of variation to fix. A specialist leasehold solicitor is worth the cost.
The government's draft Commonhold and Leasehold Reform Bill, published in January 2026, is intended to make commonhold the standard tenure for new flats in future. It is not law and no date is set; leases created now are unaffected, which is one more reason to draft them generously: 999 years and a peppercorn rent cost nothing extra today.
Planning Permission, Building Regs and Fire Safety
The conversion of a single house into two self-contained flats is a material change of use that requires planning permission. The construction work also requires building regulations approval. If either was not obtained at the time of the conversion, the property has a planning or building-control issue that needs addressing before a clean mortgage-backed sale is possible.
Planning permission options if not obtained
Certificate of Lawfulness for Existing Use (CLEUD): If the conversion has run continuously as two separate flats for the relevant immunity period, you can apply to the local planning authority for a Certificate of Lawfulness. The period is ten years where the conversion took place on or after 25 April 2024; conversions completed before that date remain under the previous four-year rule, so most older conversions are already immune or soon will be. (The change was made by the Levelling-up and Regeneration Act 2023 and applies in England only; in Wales the four-year rule still applies.) The Certificate confirms the use is lawful for planning purposes and immune from enforcement. The application fee is the same as for an equivalent planning application: £610 per flat in England from April 2026, so £1,220 for a two-flat conversion, plus solicitor support.
Retrospective planning permission: If the conversion is more recent or the immunity period has not yet been reached, retrospective planning permission may be needed. This is a normal planning application: the local authority can refuse, in which case the conversion may need to be undone or further modified.
Indemnity insurance: A short-term workaround. An insurance policy provides cover against enforcement action being taken in the future. Often acceptable to mortgage lenders and buyers' solicitors, though not all lenders accept it. Usually a one-off premium of a few hundred pounds.
Is the Planning Position Clean?
Two questions decide how much regularisation work sits between you and a mortgageable sale.
Did the conversion have planning permission when it was done?
If yes
Clean positionPlanning will not hold the split up. Building regulations and fire safety still need checking separately.
If no
Not necessarily fatalThe immunity clock may already have solved it. The next question separates the outcomes.
Has the property run continuously as two flats for the immunity period? That is 10 years where the change happened on or after 25 April 2024, 4 years before that date and 4 years in Wales.
If yes
Certificate of Lawfulness (CLEUD)£1,220 in application fees for a two-flat conversion puts the position beyond doubt.
If no
Regularise or insureA retrospective planning application (the council can refuse) or indemnity insurance where the buyer's lender accepts it.
Most decades-old conversions pass the second question and regularise cleanly; a recent conversion without permission carries real refusal risk.
Building regulations
Separate from planning. The conversion work itself (creating fire-resistant separation between the two flats, sound insulation, safe means of escape, separate utilities) should have had building regulations approval. Without it, a buyer's solicitor may not be able to certify the title to the lender's satisfaction. A regularisation certificate can sometimes be obtained retrospectively from the local building control body, depending on what was actually done.
Fire safety
Modern fire-safety expectations apply to all flats. Each flat needs adequate fire separation from the other (typically fire doors rated FD30, meaning 30 minutes' fire resistance, and 30-minute fire-resistant compartmentation) and a clear means of escape, with interlinked smoke alarms in both flats and any shared escape route. A Fire Risk Assessment (FRA) for the building may be required by buyers' solicitors and is required by the Regulatory Reform (Fire Safety) Order 2005 if the building has any common areas. Where the existing conversion does not meet current fire-safety standards, remediation work may be needed before a mortgage-backed sale.
A solicitor experienced in title splitting will identify what is needed for your specific property at the start, before you commit to the splitting process. If significant remediation is required, the cash-investor route (Option 2) may produce a better net result than splitting first.
Costs of Splitting the Title
The total cost of splitting depends heavily on whether the original conversion was done with proper planning permission and building regulations approval. A clean conversion costs much less to split than one that needs retrospective regularisation.
Splitting and lease creation costs
Solicitor fees (drafting and registering two leases): £2,000 to £5,000 plus VAT. More for complex cases or where bespoke lease provisions are needed.
Surveyor fees (floor plans and boundary measurements): £500 to £1,500.
Land Registry fees: based on the value of each flat; typically a few hundred pounds in total for two leases.
Disbursements and miscellaneous: office copies, search fees, ID checks, typically £100 to £300.
For a clean conversion with no planning issues, the total cost of splitting is usually in the range of £3,000 to £7,000.
Additional compliance costs (if needed)
Certificate of Lawfulness: £1,220 in application fees for a two-flat conversion (£610 per flat from April 2026) plus solicitor support.
Retrospective planning application: the same £610-per-flat fee (£1,220 for two flats), plus drawings and any planning consultant support.
Indemnity insurance: typically £200 to £600 as a one-off premium, depending on the property value and the issue insured.
Building regulations regularisation: varies widely. Where the work was done to a good standard, a few hundred pounds for inspection and certification. Where remediation is needed, costs can run into thousands.
Fire safety remediation: upgrading fire doors, fire separation and alarms can cost £2,000 to £10,000+ depending on what was originally installed.
Where significant compliance work is needed, the total cost of preparing the property for a mortgage-backed sale can rise to £10,000 to £20,000 or more. At that level, the financial case for splitting and selling individually starts to look closer to the as-one route, particularly for lower-value properties.
How Long Does It Take?
Realistic timelines depend on the route chosen and on whether the conversion already complies with planning and building regulations. Plan for the longer end of each range if any planning regularisation is needed.
Direct cash buyer (unsplit freehold): 3 to 6 weeks from instruction to completion. The buyer takes on any future splitting work themselves.
Auction (unsplit freehold): 4 to 8 weeks total. 3 to 4 weeks of pre-auction marketing, then 28 days from the hammer falling to completion. Often suitable for properties with planning or title complications.
Estate agent (unsplit freehold): 8 to 16 weeks. Investor-led market; higher fall-through risk than a typical sale because the buyer pool is narrower.
Split first, then sell separately on the open market: 2 to 6 months for the splitting (including any planning regularisation), then 8 to 14 weeks for each flat sale. Total: typically 4 to 9 months, sometimes longer if planning issues are extensive.
Timescale for Each of the Four Routes
Weeks from instruction to completion. The quicker the route, the lower the likely price.
Week 010203040
Direct cash buyer (unsplit freehold)
3 to 6 weeksOffer, due diligence, completion
DoneLowest price of the four routes
Auction (unsplit freehold)
4 to 8 weeksMarketing, the hammer, then completion set by the contract
DoneBelow open-market price, high certainty
Estate agent (unsplit freehold)
8 to 16 weeksInvestor-led marketing and conveyancing
DoneNarrow buyer pool, higher fall-through risk
Split first, then sell each flat
4 to 9 months2 to 6 months to split, then each flat sells on the open market: usually the highest total proceeds
Speed and price pull in opposite directions: the quickest route brings the lowest price and the slowest usually nets the most.
The most common cause of delay is planning or building-control regularisation. If the conversion was done long ago and never properly approved, getting the position fixed can take months. Where the evidence shows the immunity period has passed, a Certificate of Lawfulness puts the position beyond doubt; where it does not, a retrospective application is the fallback, and the local authority can refuse it. An early planning enquiry pays back many times over by clarifying which route is realistic.
Who Buys These Properties?
The buyer pool for an unsplit two-flat property is narrower than for a single-flat sale. Understanding who realistically buys helps you target the right marketing channel and price accordingly.
Cash investors and buy-to-let landlords. Experienced investors who buy unsplit properties knowing they may need to split the title later (or hold as one and let both flats). They expect a discount that reflects the legal work and risk they take on. Typical offer: 10 to 20 percent below the post-split combined value, sometimes more where compliance work is needed.
Property developers. Buyers with experience of refurbishment and lease creation. May add value by both refurbishing the flats and splitting the title, then reselling. Look for properties where there is genuine uplift available, not just a clean split.
Auction buyers. Mostly experienced investors comfortable with title and planning complications. Auction is well suited to unsplit two-flat properties because the legal pack discloses the position upfront and bidders price it in calmly. Sales usually complete within 28 days of the hammer; the contract sets the period.
Specialist quick-sale buyers. Direct cash buyers, including Sell Flat UK, who buy properties with title or planning complications. Price below open-market value, in exchange for speed (3 to 6 weeks typical) and certainty.
Less likely: owner-occupiers. Most owner-occupier buyers want a single flat with its own lease and a mortgage. They are not the realistic buyer for an unsplit property, though occasionally a buyer wanting to buy the whole house and live in one flat while letting the other will appear.
The investor discount is the practical reality of the as-one route. A serious investor will model the post-split combined value, deduct the cost and time of splitting and any compliance work, deduct their target profit margin and offer the residual. That is why splitting first usually produces a higher total even after accounting for the seller's own splitting costs: the seller keeps the investor's profit margin for themselves.
The comparison is before tax. If the property has been let, capital gains tax is usually in play on either route, and splitting the title can change how reliefs apply; take advice from an accountant on your own position before choosing.
What Happens to the Freehold After You Split
If you go the splitting route, the freehold title still exists and continues to sit over both leasehold flats. You need to decide what to do with it. Three common approaches:
1. Retain the freehold yourself
You become the landlord (freeholder) of the building, with both flats let on long leases. You arrange buildings insurance and deal with any landlord obligations under the leases (typically maintenance of the structure and shared parts, recovering costs through service charges). This is straightforward but does mean ongoing administrative responsibility, and you remain on the title indefinitely.
2. Transfer the freehold to a management company owned by the leaseholders
A jointly owned management company (often called a "share of freehold" arrangement) becomes the freeholder. Each flat owner has an equal share. The leaseholders collectively manage the building, arrange insurance and decide on maintenance. This is widely seen as the cleanest long-term outcome for leaseholders, and is increasingly common in newly created leases. It does require setting up a limited company at the splitting stage and transferring the freehold into it.
3. Sell the freehold separately
You can sell the freehold as a separate transaction, either as part of the original sale to one of the flat buyers or to a separate freehold investor. Newly created leases carry no ground rent, so the freehold's investment value rests on the long-term reversion alone and is usually modest; the most likely buyer is one or both of the leaseholders, who often want the control that comes with it.
Many sellers find the management-company route is the cleanest. It removes any future landlord liability, often increases the marketability of the leasehold flats (buyers value share-of-freehold) and creates a clean exit. Discuss with your solicitor at the splitting stage; the company can be set up at the same time as the leases are created, and the leases can be drafted to reflect the management-company structure.
Documents You Will Need
Whichever route you choose, the buyer's solicitor will request a defined set of documents. Gathering these early avoids the delays that often derail title-splitting sales. Some take weeks to obtain. If you market the property through an agent, a known planning or building-control problem is material information that has to be disclosed to buyers under consumer protection law (the Digital Markets, Competition and Consumers Act 2024), so establish the position before listing rather than let it surface mid-conveyancing.
Title deeds and Land Registry register: the existing freehold title document. Your solicitor obtains this from HM Land Registry.
Energy Performance Certificates (EPC): one for each flat. Must be in date (less than 10 years old). Commission separate EPCs for each unit if not already done.
Planning permission documents: for the original conversion, if obtained. If not, a Certificate of Lawfulness or evidence supporting one. The local authority's planning portal often has historical documents online.
Building regulations approvals or completion certificates: for the original conversion work. If missing, a building control regularisation certificate may be obtainable.
Fire Risk Assessment (FRA): required for the common parts under the Regulatory Reform (Fire Safety) Order 2005. Buyers and lenders will ask for it.
Gas safety certificates: for any gas appliances in either flat, current within the last 12 months (an annual gas safety record is a legal requirement where either flat is let).
Electrical Installation Condition Report (EICR): ideally for each flat and for any shared circuits (legally required every five years where a flat is let).
Draft leases (if splitting): the draft lease for each flat, prepared by your solicitor.
Management arrangements: details of any management company, service charge accounts (if existing) and insurance arrangements.
Tenancy agreements: if either flat is currently let, the tenancy agreement, deposit protection certificate and rent payment history.
For an as-one sale to a cash investor, the document requirements are lighter (the investor will deal with most of the leasehold-creation paperwork themselves). For a splitting-and-sell-separately route, the full set above will be required by each flat-buyer's solicitor.
Sell Flat UK Buys Properties Direct
If a direct sale of the whole property is the right route for your circumstances, we buy unsplit two-flat properties for cash, including those with planning, building-regulations or fire-safety issues. We assess the position together, factor any required compliance work into our offer from the start and complete typically within 3 to 6 weeks.
The trade-off is a price below open-market value in exchange for speed and certainty. It is one of several valid routes alongside auction, sale to a developer and the longer route of splitting the title and selling each flat separately on the open market. We will tell you honestly if a different route is likely to produce a better net result for your situation.
Yes, if you want to sell each flat to a separate buyer. You cannot sell an individual flat to a mortgage-backed buyer without that flat having its own leasehold title. Splitting the freehold into leasehold titles requires a solicitor to draft and register the leases at HM Land Registry, and may require compliance with any planning or building regulations conditions from when the conversion was done.
In practice, no. Mainstream mortgage lenders require a flat to have its own registered leasehold title before they will lend. A flat that is part of a single freehold title cannot be mortgaged as a separate unit. Selling either flat on its own therefore means creating its lease first. The whole building is different: alongside cash buyers, some specialist buy-to-let lenders will finance an unsplit two-flat property as a single investment.
Usually more if sold separately after splitting the title, because each flat can then be sold to a mortgage buyer at full market value. The legal and compliance costs of splitting the title need to be deducted from the uplift. Solicitor fees alone typically run to £2,000 to £5,000, plus surveyor and Land Registry fees. The net gain depends on the local market values and the condition of both flats.
An unlawful conversion can make both flats difficult or impossible to sell with mortgages until the planning position is regularised. Options include applying for retrospective planning permission, applying for a Certificate of Lawfulness if the conversion has been continuous for the relevant immunity period (ten years where the conversion took place on or after 25 April 2024, four years for conversions completed before that date; in Wales the four-year rule still applies), obtaining indemnity insurance or selling as-is to a cash buyer who is willing to take on the risk. A solicitor can advise on the specific position for your property.
Broadly: solicitor fees of £2,000 to £5,000 or more depending on complexity; surveyor fees of £500 to £1,500; Land Registry fees based on the property value (typically a few hundred pounds for two leases); and potentially planning or building regulation compliance costs if these have not previously been obtained. The total can vary significantly depending on whether the conversion was done properly in the first place.
Typically two to six months for the splitting process, then a further two to three months for each flat sale to complete on the open market. Faster routes are possible if the conversion is straightforward and all planning and building regulations are in order. Slower if planning regularisation, retrospective certificates or fire-safety remediation are needed first.
Yes. Experienced cash investors and developers will buy a single-title property knowing they will create the leases themselves after purchase. They take on the legal work, the planning compliance and the registration, and they discount their offer accordingly to reflect that effort and risk. The trade-off is a faster, simpler sale at a lower headline price than splitting the title and selling each flat separately.
Title deeds, Energy Performance Certificates (EPCs) for each flat, planning permission and building regulations approvals (or evidence of the position if not obtained), gas and electrical safety certificates, fire safety documentation including any fire risk assessment (FRA), draft leases (if you are splitting) and any management or service-charge arrangements you have set up. The buyer's solicitor will request all of these. Gathering them early avoids delays.
Ready to Get a Cash Offer for Your Property?
We buy unsplit two-flat properties, including those with planning or building-regs complications. No estate agent. No public viewings.